
Borrowing for your business for the first time in Brisbane starts with understanding what you need and how you will repay it, rather than hunting a headline rate. Your records and cash flow help a lender assess your application even without an earlier business loan to point to. Get those basics in order before comparing offers.
What lenders want from a first-time borrower
This guide is for an operating business that hasn’t borrowed before, not for an idea-stage startup with no sales yet. You’ve got customers and money coming in. You just don’t have a business loan history to point to.
A first application for business finance in Brisbane might follow a period of funding everything from cash flow. Perhaps the ute needs replacing or the cafe needs a fit-out. You might need stock ahead of a busy stretch.
Without a business loan track record, other evidence becomes important. Depending on the product and business structure, a lender may review your personal credit file alongside business records. Be ready to explain what the money is for and how repayments fit your income.
Treat repayment capacity as a separate question from the security you can offer.
Don’t build your application around the value of an asset alone. Show the pattern of deposits and what remains after operating costs, tax obligations and any owner drawings. A clear picture gives the lender useful evidence to assess, but neither tidy records nor valuable security guarantees approval.
Get your structure and records in order
Lenders can’t assess a business they can’t identify. Have your ABN active, your company registration correct with ASIC if you’re a company, and your business name tied to the right entity.
Sole trader and company structures are treated differently for income and liability. A sole trader’s personal income and business income often blur, while a company’s income sits in its own accounts. Lenders know this and they read bank statements accordingly. Keep a separate business account and run all trading income and costs through it. If you’re unsure how your structure affects tax or risk, get independent accounting or legal advice before you apply.
Gather your core records early. Depending on the product, you may need recent bank statements, business activity statements (BAS), tax returns and profit and loss statements. Ask for a document checklist. Records should be accurate, and any differences between reporting periods should be explainable.
Register for GST if your turnover requires it and keep those filings up to date. Lenders may cross-check BAS against bank deposits.
Order your personal credit file at least a month before you plan to apply and read it line by line. Fix wrong addresses or defaults you don’t recognise and allow time for errors to be corrected before a lender sees them.
Define a clear purpose and loan amount
A vague request makes a lender guess. A defined request lets it match the term and security to the purchase. Don’t apply for working capital and hope for the best. Apply for $40,000 for a second-hand excavator that lets you take on larger jobs.
Hospitality shows the other side. A Brisbane cafe owner might need $25,000 to cover wages and stock through an expected quiet period. Map that shortfall against the receipts expected to repay it. If the forecast shows losses continuing rather than a temporary timing gap, taking on debt may deepen the problem. Write down the costs and the proposed repayment source.
Borrow what the job needs plus a small buffer for freight or installation costs. Don’t double it just in case, because every extra dollar adds to the repayment you must prove you can meet.
Set a timeline too. If you need the excavator in eight weeks, say so. Check when the first repayment falls due and whether you can cover it even if the machine hasn’t started earning.
Lenders group needs by life span. Stock and wages suit short-term help that clears quickly, while machines and fit-outs suit longer terms.
Match the product to the job
Term loans, equipment finance, invoice finance, and lines of credit cover most first borrowing needs. Each one is built for a different cash-flow pattern. Work out when you need the money and when you can repay it before choosing a product.
Term loans and lines of credit
A term loan pays a lump sum upfront, repaid over an agreed term. It can suit one-off costs like a fit-out or stock purchase. Check the repayment schedule and any final balloon payment. A line of credit gives you a limit you can draw and repay within its terms. Interest is generally charged on the amount drawn, but facility fees or other charges may also apply.
Equipment finance and invoice finance
Equipment finance is tied to the asset you buy. The machine or vehicle acts as security, which can mean a longer term that lines up with its working life. Invoice finance is different. It advances cash against unpaid invoices so you don’t wait 30 or 60 days to be paid. It suits businesses that invoice other businesses and then wait for payment.
Security requirements also matter when comparing Business Loans. Read each offer’s terms alongside its repayment schedule, rather than choosing on the product name alone.
A trades business buying a ute will often look at equipment finance. A hospitality business smoothing wages may look at a line of credit or invoice finance if it caters on account. Don’t force a product to fit. If the repayments don’t line up with when money comes in, keep looking.
Understand security and personal guarantees
Secured means a specific asset backs the loan. That can be property, a vehicle, major plant, or cash held on term deposit. If you don’t repay as agreed, the contract lets the lender sell that asset to recover what is owed. Because the lender has that fallback, secured loans may have lower interest costs than the same amount unsecured.
An unsecured loan generally doesn’t require a specific asset as collateral, but it can still carry substantial personal obligations. Limits, pricing and evidence requirements vary by lender. Read the contract for guarantees and any rights over business assets rather than relying on the product label.
A first loan may also include a personal guarantee, even when the loan itself is secured. That clause says you personally pay if the business can’t. It is separate from the security and its wording matters. Read it carefully and don’t sign anything you don’t understand. Get independent legal advice before you agree to give a guarantee, and ask your accountant how the structure affects your tax.
Don’t assume a family home is automatically at risk or automatically safe. What is at risk depends on what security and guarantees are written in your contract.
Compare cost in writing, not just the rate
The headline interest rate tells only part of the story. Fees and loan terms can move the total you pay by thousands. Always ask for the full cost in writing on the same term and amount. That gives you a fair basis for comparing two quotes.
Look for establishment fees, monthly account fees, valuation or documentation charges, and early payout costs. Ask whether interest is fixed or variable and what happens if rates move. Fixed gives certainty on each repayment. Variable can move up or down over time. Write both scenarios into your budget.
You may see a comparison rate on some loan ads, but still ask for total dollar repayments over the full term, a separate fee schedule and confirmation of which charges are included. For variable-rate quotes, ask what rate assumptions the estimate uses. Check any balloon payment too.
Test the repayment against a quiet month, not your best month. If a hospitality week dips or a trade job pays late, the repayment still falls due. Leave a buffer.
Keep every quote and fee schedule together. You’ll need them when you talk to your broker or accountant.
Prove you can repay and apply carefully
Write a simple cash-flow forecast before you apply. List expected receipts and payments by month for the next 12 months, including tax, owner drawings and existing debts. Profit isn’t the same as cash available: an unpaid invoice won’t fund this week’s repayment. Include the new loan separately. As an illustrative stress test, try receipts 20% lower and costs 10% higher, then test a major customer’s late payment.
Lenders call this serviceability. They test whether cash available after costs leaves enough for repayments. Have recent bank statements, BAS, tax returns, and management accounts ready to back your numbers. Add a one-page note that explains any odd spikes or dips. Clear explanations save back-and-forth.
Assets help but they don’t decide the outcome on their own. A lender still needs to see repayments coming from trading income. Keep the focus on cash flow, not just what you own.
Choose a lender channel that fits
Eligibility criteria differ between lenders and products. Ask about minimum trading history, turnover, required records and acceptable loan purposes before submitting an application. A finance broker can help compare options from its lender panel. Ask which lenders it considers, what fees you pay and whether it receives commission.
Apply deliberately. Credit inquiries can show on your file. Get your documents ready and compare quotes before lodging one strong application. If it doesn’t proceed, pause and ask why before you try elsewhere.
For broader preparation, eligible Queensland businesses can access a free session through the Queensland Government’s Mentoring for Growth program. Cash flow and finance are among its discussion topics. Mentors offer ideas and perspective, not professional financial or legal advice, so use your accountant or solicitor for those questions.
Avoid mistakes that slow first applications
New borrowers often trip on the same habits. Applying to several lenders at once leaves a trail and muddies your story. Mixing personal spending through the business account makes income hard to establish.
Overstating income is another snag. Lenders check statements, so round numbers with no supporting records don’t hold up. Underestimating living costs has the same effect. Read every fee schedule and guarantee clause before you sign.
If you’re turned down, don’t rush to the next lender the same day. Ask what was missing and fix it, getting independent advice if liability or tax is unclear.
Your first business loan starts with a clear purpose and a realistic repayment plan. Define the job and show repayments fit even in a soft month. Keep records clean and apply once with care. Do that and you’ll give any Brisbane lender a clear picture to assess.
Image Credit: Unsplash
A stock price shows what buyers and sellers agree on at one moment, but it reveals little about the business underneath. Company filings provide the missing detail, from revenue trends and debt levels to management risks and cash flow. Learning to read these records can help you evaluate a company using evidence instead of headlines or short-term market moves.
Why Filings Are Your Friend
Public company filings follow standardized requirements, which makes them useful for comparing businesses across industries and reporting periods. Investors can search the SEC’s official company filing database by company name or ticker symbol at no cost.
Start with the business description, financial statements, and risk factors. These areas explain how the company earns money, what could disrupt its plans, and whether reported profits are producing cash. Read several reporting periods, since a single quarter can include seasonal swings or one-time expenses. If sales rose 12% while operating costs rose 20%, for example, the company may be growing without improving its underlying economics.
Key SEC Documents Explained
Each filing serves a different purpose. The annual 10-K contains audited financial statements, detailed risk disclosures, and management’s discussion of results. The quarterly 10-Q provides a more frequent update, while an 8-K reports significant events such as executive changes, acquisitions, or revised financial guidance. Proxy statements explain executive compensation and matters scheduled for shareholder votes.
A university guide to SEC filings and financials can help you identify where specific information appears. Before opening the latest report, check an earnings calendar with countdowns to see estimated and confirmed reporting dates. That helps you plan your research before new figures arrive.
Find the Numbers That Matter
Focus first on revenue, operating income, and free cash flow. Revenue shows customer demand, while operating income indicates what remains after the core costs of running the business. Free cash flow offers another view of financial health because accounting profit can include noncash items.
Next, review debt, cash reserves, and share count. Suppose a company’s profit rises from $100 million to $110 million, but its share count increases by 15%. Earnings per share could decline even though total profit improved. Also compare cash from operations with net income. A wide gap that continues for several quarters deserves investigation, particularly if accounts receivable or inventory is rising much faster than sales.
Stay Ahead of Reporting Deadlines
Create a simple research schedule instead of waiting for earnings-day headlines. A week before a report, reread the previous quarter’s guidance and write down the figures management expects. Record revenue growth, operating margin, and any company-specific measure such as subscribers, store sales, or order volume.
When the new filing appears, compare actual results with both prior guidance and the same quarter one year earlier. Look for revisions in wording as well as numbers. A new risk factor or a shortened outlook may signal a material change. Save each review in the same spreadsheet or note template so trends remain visible and emotional reactions to a single report carry less weight.
From Filings to Financial Freedom
Company research works best inside a wider financial plan. A strong filing can support an investment thesis, but it can’t determine how much of your savings belongs in one company. Position size, diversification, and time horizon still shape the risk you take.
Connect your research to the personal benchmarks discussed in the two most important numbers for financial success. Your net worth and savings rate provide context for every investment choice. If a stock decline could disrupt an emergency fund or near-term goal, the position may be too large regardless of the company’s prospects.
For your next review, place the latest 10-K beside the newest 10-Q and compare revenue, cash flow, and debt. Those three lines often tell a clearer story than the day’s price chart.
There is no single custody arrangement that fits every user. Comparing a crypto custody model for everyday use means weighing access, responsibility, recovery options and transaction habits—not simply choosing the option with the most features. Users should understand which party controls signing keys and what happens if a device, credential or provider becomes unavailable.
Separate control from convenience
In self-custody, the user is responsible for safeguarding the credentials that authorize transactions. A custodial service manages key infrastructure under its own terms and controls, while the user relies on account access and the provider’s operating policies. Hybrid arrangements may combine user approvals with provider-held infrastructure. Labels differ, so read the product’s actual explanation instead of assuming what “wallet” means.
| Consideration | Questions to ask | Trade-off to understand |
|---|---|---|
| Signing authority | Who can authorize a transfer? | More direct control may require stronger personal procedures. |
| Recovery | What verified recovery route exists? | Convenience may depend on a provider or a securely stored backup. |
| Access | Can I transact from the devices and locations I use? | Broader access can create additional account-security considerations. |
| Support | Who can help, and what can they actually restore? | Support cannot necessarily reverse an authorized blockchain transfer. |
Match the model to your routine
Someone making occasional transfers may prioritize a simple, well-understood recovery plan. A frequent user may care more about device availability, transaction review and clear records. A person holding assets for longer periods may choose a different setup from one used for regular payments. These are planning distinctions, not guarantees of safety or investment suitability.
Consider separating purposes where appropriate: one arrangement for routine activity and another for assets that are not needed day to day. If you do this, make sure you can maintain both securely. Complexity can itself become a risk when a person forgets where recovery information is stored or cannot follow their own process under pressure.
Build a recovery plan before it is needed
Read the official recovery instructions while you still have access. Identify which information is essential, where it can be stored safely, and how you would verify that a message or support request is legitimate. Never share a seed phrase or private key with a person claiming to provide routine assistance. A plan should also account for device replacement, loss of access and a trusted person needing to understand what to do in an emergency.
- Document the custody model in plain language.
- Test account or device recovery using the provider’s official process.
- Store backups separately from the device they protect.
- Set a recurring reminder to review recovery access and contact details.
- Keep a current inventory of wallet purpose without recording secrets.
Evaluate providers with specific questions
For a managed service, review supported assets, geographic availability, authentication controls, account recovery, withdrawal procedures and the service’s terms. For self-custody software, review update practices, device compatibility, backup instructions and how transaction details are displayed. Do not rely solely on ratings or promotional security claims; look for clear documentation and a process you can personally follow.
Reassess the setup when circumstances change
A custody model that once fit may become awkward after a device change, a move, a change in transaction frequency or a service update. Review whether recovery methods still work and whether trusted contact information is current. If you stop using a wallet, follow the provider’s documented closure or transfer process and keep only the records needed for your own accounting.
Be cautious about making several changes at once. Changing devices, recovery details and transaction routines together can make it harder to diagnose an access problem. Where possible, make one planned change at a time and confirm that access remains available before retiring an existing route.
A decision checklist
- Do I know who controls the signing authority?
- Can I explain the recovery process without guessing?
- Does the setup match how often I transact?
- Can I distinguish official support from impersonators?
- Have I kept secrets out of notes, screenshots and chat?
A custody choice is strongest when its responsibilities are understood before funds are moved. Review the arrangement periodically as your devices, habits or available services change. The useful goal is not maximum complexity or convenience at any cost; it is a setup whose controls and recovery steps you can consistently maintain.
Review the recovery plan before it is urgent
People often discover a recovery gap only after a device change, account lockout or unexpected event. Periodically confirm which credentials, backups and contacts are required and whether the plan remains understandable to the intended owner. The goal is practical continuity, not collecting sensitive recovery data in unnecessary places.
As transaction volume grows, informal checks become difficult to repeat. A payment operations control framework gives teams a simple way to see who may initiate, review, approve and reconcile a movement of funds. The aim is not to add approval steps everywhere; it is to make higher-impact decisions visible and reversible where possible.
Map controls to the payment lifecycle
Begin with the actual sequence used by the business: request, validation, funding, approval, execution, status communication and reconciliation. Identify where data changes, where value moves and where one person could otherwise perform incompatible tasks without review.
| Stage | Control question | Evidence |
|---|---|---|
| Request | Is the business purpose and recipient clear? | Approved source record and reference. |
| Validation | Are required fields complete and consistent? | Validation result and exception record. |
| Approval | Does this action need independent authorization? | Approver identity, time and scope. |
| Execution | Was the approved instruction the one released? | Version or batch identifier. |
| Reconciliation | Does the recorded outcome match the obligation? | Match result and unresolved differences. |
Apply stronger review to higher-risk changes
Risk is not limited to transaction size. A changed destination, unusual timing, new recipient, manual override or material change to a rule may deserve more scrutiny than a routine payment within an established pattern. Document which signals trigger a hold or second review, and who can release that hold.
Controls should remain proportionate. If every low-risk action requires the same escalation, staff may develop workarounds that are less visible than the original process. Periodically compare the written policy with actual practice and simplify steps that do not mitigate a meaningful risk.
Separate duties where practical
In a larger team, the person creating recipient data should not be the only person approving and releasing a significant instruction. Smaller teams may not achieve full separation, so use compensating reviews: sample completed activity, independently verify sensitive changes, and retain evidence of the review. The control should be specific enough that another person can tell what was checked.
- List the roles that can create, edit, approve and release instructions.
- Identify combinations that create avoidable concentration of authority.
- Define an independent check for high-impact exceptions.
- Retain the underlying record and reviewer’s decision.
- Test that the check operates during holidays and staff transitions.
Make exceptions part of the design
Urgent requests, incomplete data and delayed confirmation will happen. Decide whether an exception can proceed, who authorizes it and how it will be reconciled later. Maintain a queue with age, owner and next action. Do not let an exception disappear into an email thread or be marked complete solely because an instruction was sent.
Review whether controls work
Measure operational outcomes that reveal friction: repeated data corrections, overdue approvals, open exceptions, duplicate attempts and reconciliation breaks. Metrics are signals for investigation, not proof of misconduct or system failure. Pair them with a sample review that follows transactions from source documentation to final record.
Keep evidence proportionate and accessible
A control is difficult to sustain if its evidence is scattered across private inboxes or personal spreadsheets. Keep approvals, exception decisions and reconciliation results in an access-controlled location that the relevant roles can reach. Use a consistent reference and a short reason code so a future reviewer can understand why a decision was made without collecting unnecessary personal information.
Retention should follow the organization’s documented requirements and applicable obligations. The goal is not to keep everything forever, but to retain enough context to support operations, accounting and authorized review. Remove duplicate working copies where possible and make clear which record is authoritative.
- Can the business show who approved a material change?
- Can the released instruction be tied to its approved version?
- Are exceptions visible until evidence supports closure?
- Do finance and operations use compatible status definitions?
A useful control matrix is short, owned and tested. It connects authority to evidence throughout the payment lifecycle while allowing routine work to proceed efficiently. When the process changes, review the matrix with the teams who execute and reconcile it—not only the people who wrote the policy.
Use the matrix in day-to-day decisions
A control matrix is valuable only when operators can use it to identify the next step: which evidence is required, who approves an exception and when activity must pause. Review a sample of routine and exceptional transactions against the matrix. If a team needs informal guidance to finish the workflow, update the matrix to reflect the real operating process.
Review evidence at the close of each cycle
At a defined close point, confirm that the control record contains the current owner, required approval, execution status and exception outcome. A concise review catches missing evidence while context is still available and makes future reporting easier to support.
Applying for machinery finance becomes much easier when the business is organised before approaching a lender. A lender will usually want a clear understanding of the equipment being purchased, its cost, the financial position of the business and whether the proposed repayment fits comfortably within existing cash flow.
This is why a machinery loan application should be treated as more than a form-filling exercise. For an Indian MSME, preparing the right financial records, equipment details and repayment plan in advance can make the process more structured and help present a stronger business case.
Step 1: Define Why the Machinery Is Needed
Start with the business reason behind the purchase. Be clear whether the machine will replace old equipment, increase production capacity, improve product quality, reduce manual work or support a new business line.
Also decide whether you are buying new or used machinery. Note the model, supplier, estimated cost and expected use. A lender can assess the requirement more easily when the purchase is specific and connected to actual business operations.
Step 2: Get a Formal Machinery Quotation
Ask the supplier for a formal quotation or pro forma invoice before applying. It should mention the machinery description, specifications, price and relevant purchase details.
This document helps support the amount requested under a machinery loan. Avoid applying for an arbitrary amount. If installation, transport or other costs are part of the requirement, check whether the lender considers them and keep supporting details ready.
Step 3: Check Your Basic Eligibility
Different lenders set different eligibility conditions, so check these before starting the application. Common areas include the type and age of the business, turnover, credit profile, repayment history and existing financial obligations.
For MSMEs, business registration, GST details and Udyam registration may also form part of the assessment. Checking these requirements early prevents you from spending time on a lender whose basic criteria your business does not meet.
Step 4: Review Your Business Finances
Look at the business finances from a lender’s perspective. Revenue alone does not show whether another EMI is affordable. Review profit, cash flow, bank transactions, current loans and regular operating expenses.
Compare the expected EMI with the money normally available after essential commitments. If cash flow changes during certain months, account for that too. The requested amount should be practical rather than based entirely on future sales expectations.
Step 5: Organise the Required Documents
Prepare the machinery loan documents in one complete file instead of collecting them after the lender starts asking. Exact requirements vary, but businesses commonly need:
- PAN, Aadhaar and applicable KYC records
- Business PAN and registration proof
- GST registration and relevant returns
- Udyam or other business existence proof
- Recent business bank statements
- Income tax returns
- Audited balance sheets and profit and loss statements
- Machinery quotation or proforma invoice
- Details of current credit facilities
- Collateral records, where applicable
Check that names, addresses, registration numbers and financial figures are consistent across the documents.
Step 6: Review Your Credit and Existing Debt
Check the credit history of the business and its promoters before submitting the application. Delayed repayments, defaults or high existing obligations may influence the lender’s assessment.
List active loans, EMIs, outstanding amounts and remaining tenures. Do not leave out a facility because it seems small. Accurate disclosure makes the application easier to verify and helps you judge whether the new repayment commitment fits current cash flow.
Step 7: Compare Suitable Lenders
Do not choose a lender only because the advertised interest rate appears attractive. Compare eligibility criteria, repayment tenure, processing charges, documentation requirements, security conditions and the overall application process.
Banks and non-banking financial companies may follow different assessment approaches. Ratnaafin, for example, is an RBI-registered NBFC providing machinery and equipment financing for MSME businesses. Any option should still be evaluated against your requirement, repayment capacity and the lender’s applicable terms.
Step 8: Complete the Application Accurately
Use your prepared records while filling in the application. Turnover, ownership, address, current borrowings and machinery cost should match the supporting documents.
Submit clear copies of every requested record. The lender may review financial statements, check creditworthiness, seek additional information or conduct a site visit. Respond promptly and use exact information wherever available. Consistency matters throughout the assessment.
Step 9: Read the Sanction Terms before Accepting
Approval is not the final step. Read the sanction or offer letter carefully before accepting the finance. Check the approved amount, interest rate, EMI, repayment tenure, processing fees and other applicable conditions.
Confirm that the final structure still suits business cash flow. If any term is unclear, seek clarification before signing the agreement.
Final Thoughts
Preparing for a machinery loan application comes down to clarity, complete records and realistic repayment planning. Know what equipment the business needs, support its cost with a proper quotation and keep financial records consistent.
A well-organised application cannot guarantee approval, since every lender follows its own credit assessment, but it can reduce avoidable gaps and make the business requirement easier to evaluate. It also gives you a stronger basis for comparing offers.
For regular drivers, fuel expenses make up a significant part of the monthly budget. Many Credit Cards advertise fuel surcharge waivers as a way to reduce these costs, but the actual savings are often misunderstood. Some cardholders assume a fuel surcharge waiver means fuel is discounted, while others expect it to apply to every transaction. In reality, fuel surcharge waivers are only one part of the savings offered by fuel-focused Credit Cards. If you’re planning to start the credit card apply online process, understanding the fuel credit card benefits available can help you estimate your actual savings more accurately.
What is a fuel surcharge?
A fuel surcharge is an additional fee that may be charged on Credit Card payments made at fuel stations. The surcharge is collected by the fuel station or payment network and is separate from the fuel price itself.
Many fuel-focused Credit Cards offer a waiver or reimbursement of this surcharge on eligible fuel transactions, subject to the card’s terms and conditions.
However, the waiver:
- Usually applies only within specified transaction limits.
- May be available only at eligible fuel stations.
- Does not reduce the actual price of fuel.
- Is subject to the bank’s terms, merchant eligibility, and applicable taxes.
Understanding these conditions helps set realistic expectations.
How much can you actually save?
A fuel surcharge waiver can reduce the overall cost of filling your vehicle, but it is only one component of the total savings.
For example:
| Saving component | How it works |
| Fuel surcharge waiver | Waives or reimburses the eligible fuel surcharge according to the card’s terms. |
| Reward Points | Earned on eligible fuel transactions depending on the Credit Card variant. |
| Promotional offers | May include merchant-specific campaigns or welcome benefits. |
The overall value depends on your monthly fuel spending, the Credit Card you use, and whether your transactions qualify for the applicable benefits.
Fuel surcharge waiver vs fuel rewards
Many people are confused about these two benefits.
| Fuel surcharge waiver | Fuel rewards |
| Helps offset the surcharge charged on eligible fuel transactions | Rewards customers through Reward Points or cashback on eligible fuel purchases |
| Usually applies within specified transaction limits | Depends on the card’s reward programme |
| Does not reduce the fuel price | Adds value through rewards that may be redeemed according to the programme terms |
A good fuel Credit Card may offer both, although the exact combination differs across cards.
Looking beyond the surcharge waiver
When evaluating fuel Credit Cards, don’t compare surcharge waivers alone.
Also consider:
- Reward earning rates on eligible fuel spends.
- Grocery and utility rewards.
- FASTag benefits.
- UPI rewards.
- Annual fees and waiver conditions.
- Lifestyle benefits such as lounge access or roadside assistance.
These features often contribute more to your annual savings than the surcharge waiver itself.
Choosing the right fuel Credit Card
IDFC FIRST Bank offers the FIRST Power Credit Card and FIRST Power+ Credit Card, both co-branded with HPCL and designed for customers with regular fuel expenses. These cards provide rewards on eligible HPCL fuel purchases, grocery and utility spends, FASTag recharges, UPI transactions, and additional lifestyle benefits, depending on the card variant.
The FIRST Power+ Credit Card offers up to 6.5% savings on eligible HPCL fuel purchases, while the FIRST Power Credit Card offers up to 5% savings, subject to the applicable terms and conditions. Importantly, these cards do not offer a separate fuel surcharge waiver. Instead, the savings are delivered primarily through their reward programme and other card benefits.
Before you apply for a credit card online, compare the complete reward structure rather than focusing only on fuel surcharge waivers.
Conclusion
Fuel surcharge waivers can help reduce the cost of eligible fuel transactions, but they represent only one part of the value offered by a fuel Credit Card. Reward Points, merchant offers, and everyday spending benefits often contribute more to your overall annual savings. If you’re considering the HPCL Credit Card benefits available from IDFC FIRST Bank, focus on the complete package of fuel rewards, lifestyle features, and everyday value rather than the surcharge waiver alone.
FAQs
What is a fuel surcharge waiver?
A fuel surcharge waiver helps offset the surcharge charged on eligible fuel transactions, subject to the Credit Card’s terms and conditions.
Does a fuel surcharge waiver reduce fuel price?
No. It waives or reimburses the applicable surcharge on eligible transactions. It does not reduce the price per litre of fuel.
What other HPCL Credit Card benefits are available?
Depending on the card variant, benefits may include rewards on HPCL fuel purchases, grocery and utility spends, FASTag recharges, UPI transactions, welcome benefits, roadside assistance, and lifestyle privileges.
Can I apply for an HPCL Credit Card online?
Yes. Eligible customers can apply for a credit card online, subject to documentation, KYC verification, the Bank’s eligibility criteria, and approval.
A little over a year ago, I looked back at my monthly grocery spending and was shocked. I had been spending around $1,200 every month on groceries. Like many families, I knew grocery prices had increased, but I hadn’t realized just how much my own spending had quietly grown over time. It wasn’t because I was buying luxury items or shopping at expensive stores—I simply wasn’t paying enough attention to my spending while I was shopping. I knew something had to change.
Instead of hoping my grocery bill would somehow improve, I gave myself a clear goal: keep my monthly grocery spending below $700. It sounded simple, but in reality it wasn’t. The biggest challenge wasn’t creating a budget—it was sticking to it. Every time I went grocery shopping, I had no idea how much I had spent until I reached the checkout. By then, it was already too late to make changes.
Looking for a Better Way
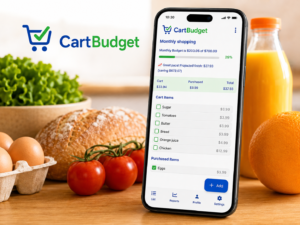
Like many people, I tried the obvious solutions. I reviewed receipts, checked my bank statements, experimented with spreadsheets, and downloaded budgeting apps. They all helped me understand where my money had already gone, but none of them helped me while I was still walking through the grocery store. I realized I didn’t need another budgeting report after I got home. I needed something much simpler. I needed to know exactly how much I was spending before I reached the checkout.
When I couldn’t find an app that worked the way I wanted, I decided to build one myself. I wasn’t trying to start a business or launch a startup. I simply wanted a tool that would help me stay on budget while I was shopping. That early version eventually became CartBudget.
Changing the Way I Shopped
For the next five months, I used the app every single time I went grocery shopping. Before entering the store, I already had a spending target in mind. As I placed items into my cart, I entered each item into the app and watched my running total increase in real time. Instead of guessing what my final bill might be, I knew exactly where I stood throughout my shopping trip.
One shopping trip stands out in particular. I was approaching the spending limit I had set for that trip when I noticed my running total getting close to my target. Instead of continuing to fill my cart, I paused, reviewed what I had already selected, and removed a few non-essential items that could easily wait until my next visit. I walked out of the store having spent exactly what I intended to spend. That simple habit eventually became routine. Instead of reacting after I had overspent, I was making better decisions before I paid.
Small Habits Produced Big Results
Over time, I realized the app wasn’t simply tracking my spending—it was changing the way I shopped. Every grocery trip contributed to my weekly and monthly budget, and because I could see my spending at any moment, I naturally became more aware of every purchasing decision. Whenever I noticed I was getting close to my monthly spending limit, I slowed down. Instead of automatically putting another item into my cart, I started asking myself simple questions: Do I really need this today? Can this wait until next week? Will this item last longer than another option?
Those weren’t difficult questions. The difference was that I was asking them before reaching the checkout instead of after getting home. The app didn’t make those decisions for me—it simply gave me the information I needed at the exact moment I needed it.
I also started paying attention to my average grocery spending per trip. Rather than focusing only on my monthly total, I challenged myself to make every shopping trip as efficient as possible. I found myself comparing one trip to the next, looking for ways to reduce unnecessary spending while still buying everything my family needed. Those small improvements added up surprisingly quickly.
The Month Everything Clicked
One month stands out more than any other.
By May, using the app had become second nature. I wasn’t consciously thinking about budgeting anymore because the routine had become automatic. Before every shopping trip, I knew roughly how much I wanted to spend. During the trip, I tracked every item I placed in my cart. If my running total started getting too close to my target, I simply made a few adjustments before reaching the checkout.
At the end of the month, I opened my monthly spending report and saw something I honestly wasn’t expecting.
I had spent only $420 on groceries.
I actually looked at the report twice because I couldn’t believe it. My original goal had been to stay below $700, yet I had finished almost $300 below that target. Compared with the previous year, when I had been spending around $1,200 each month, I had reduced my grocery spending by approximately $700.
That was the moment I realized this wasn’t luck.
The system was working.
More Than Saving Money
Saving money wasn’t the only benefit.
Before using the app, I would occasionally forget an important grocery item and end up making another trip to the store later in the week. Those extra trips often led to buying things I hadn’t planned to purchase in the first place.
Once I started planning every shopping trip and tracking everything in one place, those extra trips almost disappeared. I always knew what I needed, what I had already spent, what my average grocery trip looked like, and how close I was to my weekly and monthly budget. Shopping became more organized, more efficient, and much less stressful.
Why I Released CartBudget
After using the app privately for five months and seeing how much it had changed the way I shopped, I started wondering whether other families were facing the same challenge. Most budgeting tools help people understand where their money went after they’ve spent it. Very few help people make better spending decisions while they’re still shopping.
That’s why I decided to refine the app and release it publicly as CartBudget.
My goal isn’t to tell people how much they should spend on groceries because every household is different. My goal is to help people understand where they stand before they pay, build better shopping habits, and feel more confident about their grocery spending.
Looking back, I don’t think the biggest lesson was learning how to spend less. It was learning that small decisions made before checkout often have the biggest impact on the monthly total. Grocery prices may continue to rise, but understanding your spending while you’re still shopping is something every family can control.
Sometimes saving money isn’t about buying less.
It’s about making better decisions before you reach the checkout.
Barry Blanchard is the founder of CartBudget, a grocery budgeting app designed to help shoppers track their grocery spending in real time, stay within budget, and monitor their weekly and monthly spending before reaching the checkou
Do your kids complain whenever they have to go with you to the grocery store? What if you could transform a weekly chore into regular special moments with your kids? Any parent can do this. It’s so easy! In fact, Tom from Atlanta, Georgia did created a moment with his nine-year-old son without even trying.
His son had a light-bulb moment while standing in front of all the chips. He told his father that he suddenly understood why there are 15 kinds of potato chips, correctly recalling the term “spontaneous order” from the Tuttle Twins books. And just like that, Tom realized that everything he’d been reading to his son had been sinking in!
PHOTO: Tuttle Twins
Start with Books
You can be part of the growing movement of parents like Tom who are learning how to teach kids about money while their children are still young. Doing this is as easy as finding the right books. The Tuttle Twins series includes books that teach kids about inflation, central banking and the Federal Reserve, the economic system, entrepreneurship, and much more.
Books will help you lay the foundation you need as you learn how to teach kids about money. That’s right. Teaching kids free market economics is a snap! And the basis of understanding finance lies in realizing how the economic system works, something many kids wouldn’t normally be exposed to until high school.
Books that teach kids about inflation and the free market are essential for laying the groundwork for understanding the real world. The Tuttle Twins books break down these complex topics into easy-to-understand ideas in an exciting, engaging way that will help them retain what they learn. All the books in the Tuttle Twins series transform learning into a fun adventure through a magical journey of discovery, both for the twins and for readers!
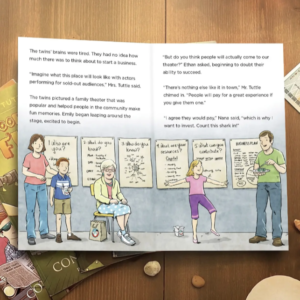
PHOTO: Tuttle Twins
Heading to the Grocery Store
The next step in teaching your kids free market economics is to take them to the grocery store. You may face some whining at first, but once you start explaining how what they’re reading in the Tuttle Twins books and other titles like them, your kids will quickly start paying attention. While at the grocery store, ask them questions like:
- If you could buy just three items today, which ones do you actually need to stay alive and which are wants that would simply be nice to get?
- When we pay for our items, why are both we and the cashier happy with the trade?
- If there aren’t many boxes of your favorite cereal left on the shelf, but it’s a very popular cereal, what do you think will happen to the price?
- Why do you think watermelon is cheaper and easier to buy in the summer but more expensive during the winter?
- Why do you think better-tasting products or more-attractive packaging is important for sales?
- Where would you choose to shop if two stores sell the same brand of milk, but one store charges $5 and the other only charges $3.50?
- How do you decide whether to purchase a less expensive brand of a product and save the rest of our money or buy the more expensive brand?
- How many people had to work to get a single box of cereal to the store shelf?
Your kids will always remember when their mom or dad took them to the grocery store and took the time to ask them questions like these. Grocery store trips don’t have to be nothing but a chore. They can become the times your kids remember the most when they get older!
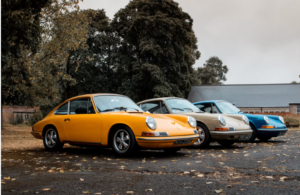
Image credit: Unsplash
Many people have a lot of their money tied up in things they rarely think about. Beyond your home or investments, you might own unique items with a lot of hidden value. Things like family heirlooms, collectibles, old electronics, or classic cars can all be turned into cash if you know how to figure out what they’re worth and where to sell them.
This guide will show you how to find, value, and sell your unique assets to unlock their financial potential.
Identifying Hidden Value
First, make a list of everything you own. Look past everyday items and think about things that might appeal to a specific group or have historical importance. This could be anything from rare comic books in your attic to a piece of art you inherited. Many assets have value that isn’t obvious, even things we don’t think of as physical property.
Some collectibles and specialty items can even become great investments when they are rare, well-preserved, and in strong demand.
Consider these types of items:
- Collectibles: Stamps, coins, trading cards, and memorabilia.
- Vintage Items: Classic cars, antique furniture, retro clothing, and old electronics.
- Art and Jewelry: Paintings, sculptures, and fine jewelry.
- Intellectual Property: Royalties from a book, song, or patent.
To understand the potential of these items, you need to look at them not just for sentimental reasons but for their market value. Different intangible asset valuation methods can help you start to understand what something might be worth, even if you can’t physically hold it.
Specialized Valuation Methods
Unlike stocks or real estate, unique assets don’t have a simple, fixed price. Their value depends on how rare they are, their condition, how much demand there is for them, and their provenance. Getting an accurate appraisal almost always means you need a specialist. For example, an appraiser for fine art uses different standards than someone who values vintage watches.
The same goes for classic cars. A regular mechanic can’t give you an accurate market price for a collector’s vehicle. Getting an expert Porsche valuation, for instance, requires deep knowledge of specific model years, how well a car has been restored, and current auction trends. For any high-value item, find a certified appraiser or a reputable dealer who specializes in that exact category. They can give you a formal appraisal document, which is important for insurance and for selling the item.
Connecting with Buyers
Once you have a reliable valuation, the next step is finding the right buyer. The best place to sell depends entirely on the asset. General marketplaces like eBay might work for lower-value collectibles, but they aren’t ideal for high-end items where trust and security are key.
For more valuable assets, think about these options:
- Auction Houses: Places like Sotheby’s or Heritage Auctions serve serious collectors and can often get the highest prices for rare items.
- Specialized Dealers: Businesses that focus on a specific niche, such as antique furniture stores or classic car buyers, already have a network of interested clients.
- Consignment Shops: A good choice for designer clothing, jewelry, and high-end accessories. The shop handles the sale and takes a percentage of the final price.
- Online Marketplaces: Niche websites for specific collectibles, like Reverb for musical instruments or Chrono24 for watches, connect you directly with enthusiasts.
Navigating the Sales Process
Selling a unique, high-value asset involves more than just agreeing on a price. A smooth and secure transaction needs careful planning and paperwork. First, gather all relevant documents, including the appraisal, certificates of authenticity, and any maintenance or history records. High-quality photos from different angles are also essential.
When you find a potential buyer, be ready to negotiate. Use your formal appraisal as a starting point and be clear about the lowest price you’ll accept. For the transaction itself, always use a secure payment method. For very large amounts, an escrow service protects both you and the buyer by holding the money until the item has been delivered and checked. Finally, figure out how the item will be shipped or delivered. For fragile or large items, professional packing and insured shipping are a must.
Taking the time to properly value and market your unique assets can give you a surprising financial boost. It all starts with recognizing the potential value sitting in your own home.
Baggage problems can turn a well-planned journey into a stressful experience, especially when essentials are missing after landing. Many travellers assume the airline will take care of every loss, delay, or damage issue.
However, airline compensation and baggage claims under insurance work differently. Understanding this difference helps travellers know whom to approach, what documents to keep, and how to make a smoother claim after an unexpected baggage issue.
What Is Airline Compensation for Baggage Loss or Delay?
Airline compensation is the amount an airline may pay when checked-in baggage is lost, delayed, or damaged while under its responsibility. The process usually begins with reporting the issue at the airport and getting written acknowledgement from the airline.
Situations Covered by Airlines
Airlines generally handle baggage concerns that occur after check-in and before the bag is returned to the passenger. This support depends on the airline’s policy, route, ticket conditions, and applicable aviation rules.
Common situations may include:
- Checked-in baggage not arriving at the destination
- Baggage reaching later than the passenger
- Damage caused while the bag was in airline custody
- Missing contents reported as per airline procedure
- Reasonable essential expenses during baggage delay
Compensation Limits Imposed by Airlines
If your checked baggage is delayed, damaged, or lost during a trip, the airline’s compensation may not always cover the full inconvenience or additional expenses you face. This is where travel insurance may offer wider support, subject to the policy terms, coverage limits, and claim approval.
Airline limits may consider:
- Whether the baggage is delayed, lost, or damaged
- Depreciated value of belongings
- Receipts or purchase proof
- Restricted categories under airline rules
- Claim timelines mentioned by the airline
Rules Governing Airline Liability
Domestic and international flights may follow different standards. For overseas travel, international conventions and airline conditions of carriage can influence how compensation is assessed.
Key factors include:
- Route and destination
- Airline terms and conditions
- Type of baggage issue reported
- Proof submitted by the traveller
- Time taken to report the concern
What Is a Baggage Claim under Travel Insurance?
A baggage claim under travel insurance is a request made to the insurer for covered baggage-related losses during a trip. It may apply when baggage is delayed, lost, or damaged, depending on the plan chosen and the policy wording.
Coverage for Lost, Delayed, or Damaged Baggage
If you are travelling to the USA with checked luggage, even a short baggage delay can affect your plans, especially when essentials are not immediately available. While choosing travel insurance for the USA, check whether the policy includes baggage delay, baggage loss, or baggage damage benefits, along with the claim limits and required documents.
Coverage may include:
- Loss of checked-in baggage
- Delay in receiving checked-in baggage
- Damage to covered baggage
- Reimbursement for approved essential purchases
- Support based on the policy schedule
Additional Protection beyond Airline Responsibility
Airline compensation focuses mainly on the airline’s responsibility. Insurance, on the other hand, may provide broader trip-related protection.
Insurance may offer added support for:
- Trip-related inconvenience caused by baggage delay
- Covered purchases made during the waiting period
- Documentation-based reimbursement
- Assistance during international travel
- Claims handled as per policy terms
Policy Terms and Coverage Limits
Every travel insurance policy has defined benefits, limits, conditions, and claim requirements. A traveller should not assume that every baggage issue will be treated the same way.
Important points to review include:
- Covered baggage benefits
- Claim limits for each benefit
- Required documents
- Reporting timelines
- Terms linked to unattended items or valuables
Key Differences Between Baggage Claims and Airline Compensation
Both options help travellers deal with baggage issues, but they differ in payer, scope, limits, documents, and settlement process.
Who Pays the Compensation?
Airline compensation is paid by the airline when the baggage issue falls under its responsibility. The insurer pays a baggage claim under insurance after reviewing the claim against the policy terms. In some cases, both processes may be relevant, but they remain separate.
Difference in Coverage Scope
Airlines usually focus on baggage handled during air travel. Insurance may consider wider travel-related situations covered under the policy. This is why travellers should review both airline rules and insurance benefits before starting an international trip.
Variation in Claim Limits
Airline liability usually follows defined limits and may not reflect the complete inconvenience faced by the traveller. Insurance claim limits depend on the plan selected. A policy with suitable baggage benefits can help travellers prepare better, provided the claim meets policy conditions.
Documentation Requirements
Airlines usually ask for a baggage report, baggage tag, ticket details, and proof of loss or expenses. Insurers may ask for these along with a claim form, identity proof, boarding pass, receipts, and airline communication. Keeping documents organised improves clarity during assessment.
Time Taken for Settlement
Airline resolution may depend on tracing the bag, reviewing responsibility, and verifying supporting documents. Insurance settlement may depend on claim submission, document review, and policy terms. Travellers should report the issue quickly and follow the required process to avoid unnecessary delays.
Conclusion
Airline compensation and baggage claims under insurance serve different purposes. Airlines address baggage issues linked to their handling responsibility, while insurance may support travellers through covered benefits under the chosen policy. For Indian travellers going abroad, understanding both processes can reduce confusion during stressful moments. The practical approach is simple: report the issue immediately, collect documents, read the policy wording, and submit claims with complete information.