
Image Credit: Unsplash
When a financial emergency hits, most people immediately think of using a credit card or getting a personal loan. These can give you quick cash, but they often cost a lot in the long run. The good news is you have many other ways to get financial help without getting stuck with high-interest debt. Looking into options like community support or direct negotiation can protect your financial future while solving your immediate problem.
The Traps of High-Interest Debt
High-interest debt, like credit cards and payday loans, can quickly become a huge burden. The main issue is how interest builds up, making it hard to pay off the original amount you borrowed. Many people find their monthly payments barely cover the interest, while the main debt stays high. This often leads to what experts call the debt trap cycle.
Imagine you have a $2,000 emergency car repair and put it on a credit card with a 24% annual percentage rate (APR). If you only make the minimum payment, it could take years and cost thousands in interest to pay off just that one expense. The quick relief of fixing your car is then replaced by the constant stress of growing debt.
This cycle can really hurt your overall financial health. It can affect your credit score, your ability to save, and your mental well-being. Understanding this risk is the first step to finding better solutions. Learning how to escape the debt spiral means realizing that borrowing isn’t the only answer when you’re in a tough spot.
Exploring Debt-Free Alternatives
Before you borrow, take time to look for debt-free ways to get money. You might be surprised by how many programs are out there to help during hard times. These options won’t add to your financial stress and are made for people facing temporary difficulties.
- Government Assistance Programs: Federal, state, and local governments offer many support services. Programs like the Low Income Home Energy Assistance Program (LIHEAP) can help with utility bills, and the Supplemental Nutrition Assistance Program (SNAP) can help with groceries. You can often find a full list of available aid on your state’s Department of Health and Human Services website.
- Non-Profit and Charitable Organizations: Many non-profits and local charities offer emergency financial help. Groups like The Salvation Army, Catholic Charities, and local community action agencies often have funds to help people with rent, medical bills, or other essential costs. A quick search for “emergency financial assistance” in your area can bring up many options.
- Generating Quick Income: Don’t forget about what you already have. Selling things you no longer need on sites like Facebook Marketplace or Poshmark can get you cash fast. You could also try a temporary side job, such as pet-sitting, delivering food, or freelance work related to your skills. While this isn’t outside help, it lets you solve the problem yourself without taking on debt.
Leveraging Community Support
Sometimes, your community is your most powerful resource. Friends, family, and even strangers are often willing to help when they understand your situation. In today’s digital world, it’s easier than ever to ask your network for support through crowdfunding. This lets many people contribute small amounts that together solve a bigger financial problem.
Crowdfunding works especially well for specific, one-time needs, like unexpected medical bills, emergency home repairs after a storm, or covering income gaps after losing a job. The key to a successful campaign is being open and honest. Clearly explaining your situation, what the money is for, and how it will help build trust with potential donors. Many people find it easier to ask for help this way than face-to-face. For those in a crisis, a practical step is to start an online fundraiser and let their community help.
Unlike a loan, money raised through community support doesn’t need to be paid back. This means you can handle your immediate financial need without creating future debt. It’s a method built on goodwill and strengthens community ties by letting people support each other in meaningful ways.
Negotiating Payment Plans Effectively
If you have a big bill from a hospital, a utility company, or even your landlord, don’t assume you have to pay the full amount. Many organizations have hardship programs and are open to setting up a payment plan that fits your budget. The important thing is to be proactive and talk to them before your account becomes overdue.
When you call, be ready to discuss your situation calmly and honestly. You don’t need to share every detail, but a simple explanation like, “I’ve had an unexpected loss of income and am having trouble paying the full amount right now,” can open the door to a solution. Instead of just saying you can’t pay, suggest a plan. For example, you could ask, “Would it be possible to pay $100 a month for the next six months to catch up?”
Here are some tips for a successful negotiation:
- Call Before the Due Date: This shows you’re acting in good faith and gives you more options.
- Be Polite and Patient: The person on the phone is more likely to help if you stay courteous.
- Know Your Numbers: Understand what you can realistically afford to pay each month.
- Get it in Writing: Once you agree on a new plan, ask for an email or letter confirming the terms. This protects you from future misunderstandings.
Negotiating directly with creditors is a powerful way to get out of debt or avoid it completely. These arrangements often don’t charge interest and are one of the most effective ways to pay off debt faster because every dollar goes toward the main debt.
Facing a financial shortage is stressful, but it doesn’t have to lead to long-term debt. Taking time to explore alternatives, ask for support, and communicate with creditors can help you manage the situation without adding financial strain. Every challenge is different, but making informed decisions now can protect your finances, reduce stress, and give you a stronger foundation for the future.
Image credit: Unsplash
When you run a service business, your profits depend directly on the value you offer and how efficiently you operate. While getting more clients is always good, real financial success comes from truly understanding your business model. This means setting the right prices, keeping costs down, and making sure your quality of work keeps clients coming back. Making your service business more profitable isn’t about chasing every new lead; it’s about making your core processes stronger.
Understanding Your Service Value
The first step to earning more is to clearly define and price what your service is worth. Many business owners charge too little because they’re afraid of losing customers. But your pricing should cover not just the time you spend, but also your expertise, convenience, and the results you deliver. Add up all your direct and indirect costs, include your desired profit, and see what competitors are charging. Don’t just try to be the cheapest. Instead, explain clearly why your service is valuable enough to justify your rates. If your service is better and more reliable, clients are often willing to pay more for it.
Optimizing Operational Costs
Profit isn’t just what you make; it’s also what you manage to keep. Tracking and controlling your operating costs is crucial for increasing your profit margins. Regularly reviewing expenses, from supplies and transport to software subscriptions and marketing, is a key part of managing your business finances well. It helps you spot where money is being wasted, which costs can be reduced, and which expenses are actually helping the business grow.
For instance, a landscaping company could plan its daily routes better to save on fuel, or a consulting firm might switch to cheaper project management software. Small, consistent savings add up over time and directly boost your profits.
Quality Control as a Profit Driver
In a service business, mistakes cost a lot. They lead to rework, wasted materials, and damage to your reputation. A strong quality control system isn’t just an expense; it actually drives profit. By making your service delivery consistent, you ensure quality and reduce errors. This is especially important for businesses with many employees or teams, like cleaning services, maintenance crews, or field technicians.
For example, using a detailed checklist on a janitorial app for property inspections makes sure every task is done to the same standard each time. This proactive approach prevents client complaints and avoids the expensive process of fixing problems later.
Client Satisfaction and Retention
Happy clients mean more profit. It can cost five times more to get a new customer than to keep an existing one. High-quality service directly leads to happier clients, which then improves retention rates. When clients trust you to do the job right every time, they’re more likely to sign long-term contracts, refer others, and be less concerned about price increases. Make it easy for clients to give feedback and act on their suggestions. This not only helps you improve your service but also shows them you value their partnership, strengthening the relationship and their loyalty.
Leveraging Technology for Growth
Modern technology offers powerful tools to streamline operations and help your business grow. Beyond quality control, technology can automate administrative tasks, improve communication, and expand your marketing reach. Customer Relationship Management (CRM) systems help you track interactions with clients and potential clients, while scheduling software can optimize your team’s time. These tools free you up to focus on high-value activities that directly bring in revenue.
Ultimately, building a more profitable service business is about constantly improving. Start by focusing on one area, whether it’s tightening your budget or using a new quality checklist, and build from there.
As global investing and international banking evolve, GIFT City has emerged as a key financial hub for Non-Resident Indians. A gift city account allows NRIs to use international banking services while being connected to India’s financial ecosystem.
Understanding how this account works, along with its features and benefits, can help NRIs make more informed decisions about managing global income.
What is a GIFT City account?
A gift city account is a foreign currency savings account offered through India’s International Financial Services Centre (IFSC) at GIFT City. It allows NRIs to hold, manage, and transact in prominent foreign currencies such as USD, EUR, GBP without converting funds into Indian rupees. This sets it apart from traditional NRE/NRO accounts, which need to be maintained in Indian rupees.
Key features of a GIFT City account
The GIFT account offered by IDFC FIRST Bank is known as First Global Savings account and it comes with a range of features designed for global banking needs:
| Feature | Details |
| Foreign currency holding | Maintain funds in USDEUR & GBP without conversion |
| Competitive interest rates | Earn interest in foreign currency(e.g. approx. 4.50% on USD Savings account) |
| Interest credits | Interest is credited monthly |
| Freely repatriable funds | Transfer money abroad without restrictions |
| Zero-fee banking | No account maintenance charges |
| No minimum balance | Zero average monthly balance requirement |
| Tax advantages | Interest earned is presently not taxable in India |
| Multicurrency support | Supports major global currencies like USD , EUR, GBP |
| Single app access | Manage NRI and GIFT City accounts in one app |
| Fully digital experience | Open foreign currency fixed deposit online by debiting your First Global Savings account |
These features position the GIFT city account as a global banking solution as opposed to a traditional savings account.
Benefits of opening a GIFT City account
Beyond just features, a gift city account provides some really useful benefits for NRIs, making things more convenient and straightforward.
- Global banking from India: Access international financial services
- Better returns on foreign currency: Interest rates may be more competitive compared to some international banks.
- No currency conversion loss: Funds remain in foreign currency, avoiding exchange rate fluctuations.
- Tax efficiency: Interest earned would be tax-exempt in India
Seamless international transfers: Send money globally with facility of transferring funds abroad via mobile app. These benefits make it particularly useful for NRIs who earn and invest internationally.
How can an NRI open a GIFT City account with IDFC FIRST Bank?
You can open a GIFT City savings account by logging into your IDFC Bank Mobile banking application* or by contacting your dedicated relationship manager assigned to your NRE/NRO Account.
What NRIs should know before opening
Before opening a Gift City account, it is useful to consider the following:
- It is available only to eligible non-residents and overseas citizens of India
- Funds are maintained in foreign currency, not INR
- Tax treatment may differ based in your country of residence
Understanding these aspects helps in using the account effectively.
Why GIFT City accounts are gaining importance
A Gift City account provides a welcoming step towards global banking for NRIs. It offers the convenience of foreign currency access, tax benefits, and easy digital management, helping to smoothly connect the domestic and international financial worlds. As GIFT City continues to expand, these accounts are becoming increasingly important for NRIs to manage, invest in, and build their wealth worldwide.
Choosing a family health plan without first studying medical needs can turn a sensible purchase into a stressful decision later. Every household has different routines, health histories, medicines, preferred doctors, and future expectations.
A plan that looks suitable on paper may feel limited during actual use. Before buying health insurance, families should slow down, compare details, and match coverage with real healthcare habits rather than assumptions.
Why Understanding Family Medical Needs Matters
Family medical needs are not limited to hospitalisation. They include regular consultations, diagnostic tests, maternity planning, child care, senior care, ongoing medication, and preventive check-ups. A thoughtful review helps you choose coverage that supports everyday realities, not only rare emergencies.
- List existing conditions and regular prescriptions.
- Note how often family members visit doctors.
- Consider age, lifestyle, and family health history.
- Review whether dependants need specialised care.
- Think about preferred hospitals and treating doctors.
Financial Costs of Choosing the Wrong Plan
A poorly matched plan may lead to avoidable strain through higher personal payments, repeated reimbursements, or benefits that do not fit actual usage.
Higher Out-of-Pocket Expenses
Out-of-pocket expenses can rise when the plan structure does not match how your family seeks care. Frequent consultations, recurring tests, or specialist visits may feel manageable individually, but together they can affect the household budget. Families reviewing broader protection may also consider critical illness insurance for serious diagnosed conditions, subject to policy terms.
- Review what you may need to pay yourself.
- Check limits linked to hospital rooms or procedures.
- Understand how deductibles affect claims.
- Compare benefits with your usual medical spending pattern.
Unexpected Medical Bills
Unexpected bills often appear when families assume every medical situation will be handled in the same way. Coverage terms can differ for daycare procedures, pre-hospitalisation tests, post-hospitalisation care, ambulance services, home care, and specific treatments. Reading the policy wording may not be exciting, but it can prevent confusion during stressful moments.
- Check which services are included under the plan.
- Review claim processes before treatment is needed.
- Keep records of consultations, prescriptions, and reports.
- Ask clear questions when a term seems unclear.
Insufficient Coverage Limits
Some plans may look adequate at purchase, yet feel restrictive when multiple family members need care within the same year. Coverage limits, sub-limits, and disease-specific conditions can influence how useful a plan feels during treatment. Families should look at the overall protection amount, not just the premium, while keeping affordability in mind.
- Look at the sum insured in relation to family size.
- Check whether limits apply to specific treatments.
- Review restoration or recharge benefits carefully.
- Consider future medical needs, not only current comfort.
How to Assess Your Family’s Medical Needs before Choosing a Plan
Assessment should be practical and honest. Start with current health realities, then consider what may reasonably arise over the next few years.
Review Current Health Conditions
Write down diagnosed conditions, regular medicines, allergies, previous surgeries, and ongoing therapies for every family member. This helps you compare waiting periods, coverage terms, and claim requirements with more clarity. It also reduces the chance of overlooking health details during proposal submission.
Consider Expected Healthcare Needs
Families should think about planned treatments, maternity expectations, children’s health needs, dental or vision-related concerns, and care for ageing parents. These needs may differ across life stages, so the plan should suit both present responsibilities and likely future healthcare use.
Evaluate Healthcare Usage Patterns
Look at how often your family consults doctors, undergoes tests, buys medicines, or visits hospitals. A family with frequent outpatient needs may value different features than one that mainly wants protection for hospitalisation. Usage patterns make comparison more realistic.
Compare Coverage Features Carefully
Do not compare plans only by premium. Review inclusions, waiting periods, claim support, cashless options, renewal conditions, add-ons, and wellness benefits. A balanced comparison helps you see whether the policy design suits your family’s medical priorities and comfort level.
Check Provider Networks
A useful plan should give access to hospitals and healthcare providers that your family can realistically visit. Check whether preferred hospitals are in the cashless network, especially near your home, workplace, children’s school, or parents’ residence. Convenience matters during urgent situations.
Conclusion
Choosing a health plan before understanding your family’s medical needs can affect both care and finances. The right approach begins with a careful review of conditions, habits, preferred providers, and expected requirements. Families that compare plans with these details in mind usually make more confident decisions. Insurance should support real life, not just look suitable on paper, so take time to assess before you choose.
If you feel as though your life isn’t quite where it should be, or if you know that you are struggling to deal with things regularly, then it may be time for you to start practicing some self-care. This guide will help you to do just that, so you can get things back on track in no time at all.
Source: Pexels
Get in Shape
One of the main things you can do is try to get in shape. Strong bodies and strong minds often go hand-in-hand, so make sure that you forget about how your gym routine is making you stressed and how it’s something extra to have in your day, and instead focus on how it makes you feel when you have done it. If you can do this then you will find it easier to not only make sure that you’re dedicated, but also making sure that you are reminding yourself that you are capable of way more than you once were. Fitness isn’t about doing push-ups; many people find it to be a way to reclaim their power, and this is great to say the least.
Get out a Bit
Sometimes you may feel as though you need to get out of town for a little bit. If this is the case, then try to make sure that you take a day, or even a week, and escape your usual town. If you can do this, then you may find that there is a whole world of things to explore, right on your doorstep. Sometimes a change in scenery helps you to breed a change in mindset, and being away from home gives you the chance to feel a bit of tranquility, but on your own terms. You may also find that it breaks the cycle that you are in, which is a good way for you to start feeling like you are able to enjoy yourself once more.
Take Control of Your Story
Taking control of your story is one of the best things you can do. The past is simply a story that you will repeat time and time to yourself. If you can take the time to understand it, then you may find that it is very liberating. Visit a therapist who can help you to reframe the experience you have had or even take the time to journal it, as this is a good way for you to gain a better understanding of what has happened to you. If you can learn to pinpoint the opportunities you have for growth, then this will help you in more ways than one.
Invite New People
Sometimes, inviting some new people into your life is the best thing to do. The positive effect that people have on others can sometimes be immeasurable. Sometimes the best thing you can do to try and heal from the toxicity of people is to try and make sure that you find new relationships that help you to flourish. Make sure that you do not hide or even downplay anything that feels like it is important to you, and again, do not apologize for where you have been in your life.
Seek Professional Help
Sometimes, if you have been in a bad situation, you need to find ways to try to break out of it. One way you can do that would be for you to seek professional help. Professional help can be speaking to a counsellor, or it can be trying to open up to someone who can help you with your debt or your financial situation. If you have been involved in a criminal offense, then seeking the help of a professional lawyer could be a good way to get the legal support you need. DCD LAW is a great option if you feel you need proper representation, and when you go through their service, you will find it easier than ever to not only feel content that you are in good hands, but that you are also able to get the outcome you want.
Be Disciplined
Another good thing to do would be for you to make sure that you are disciplined about your self-care. When you are sick, you may find that you have to take time to rest and to put your feet up. The issue is that if you don’t do this, then you end up burning yourself out even more. If you take this same approach to your mental health, then you will find that it is easier than ever for you to make sure that you are not harming yourself without even realizing it.
Change your Appearance
Changing your appearance is sometimes the best thing you can do. It may be that you need a more deliberate change to reflect your internal change. By altering your style, your make-up, or even your hair, you may find that you can welcome an even nigger change in your life, which is great. It’s also a good idea for you to change what you don’t feel is working for you. When the stakes are high and your life is a little down, it’s a good idea to make sure that you are taking steps to not only try to make sure that you are taking care of yourself but also to make sure that you are acknowledging the things that you are finding hard.
Connect with People
Another thing to do would be for you to try to connect with people who have been through something similar to what you have been through. Get some works of wisdom and also try to read their stories. Now would also be the time for you to try to use the wisdom you have gained over the years to try to support your own journey. Sometimes you need to try to find other people who have been through what you have so you feel less alone. Sometimes unplugging from your device can help too. Take a full week of your life and try to spend as much time outdoors. If you can do this, then you will find it easier not only to make sure that you’re able to connect with the natural world but also to make sure that you’re not running yourself into the ground by trying to be everything to everyone around you.
Buying your first home is an exciting experience. However, it is also a major legal and financial commitment. When added to the impact that it will have on your daily life over the years to come, it is understandably a stressful moment too.
With the right approach, though, it is possible to stay in control throughout the process. Here are some of the most effective ways you can do this in style.
Timing: Focus On Your Circumstance
There has been a lot of talk about the timing of buying a home in recent months. Debates on whether 40 is actually the right time have become increasingly common as a result of statistical trends. Meanwhile, the market itself has been a little less stable in the post-covid era. As such, there have been doubts whether buying is smarter than renting at all.
Ultimately, the advice should be clear: do what works for you. It is far more important to weigh up your finances and current life status, including relationships and career, than worry about your age. Whether you’re 20 or 60, the right time for you is the right time for you.
Legalities: Protect Yourself With The Right Support
As well as being a major legal process, it’s one you have not experienced before. Therefore, it is vital that you get the very best professional support. A dedicated solicitor can guide you through the whole process. As well as understanding the admin and conveyancing fees, it ensures that compliance needs are met at all times. This prevents future repercussions.
Protecting yourself on a legal front isn’t just about money. It also ensures that the process is completed on time, meaning you can move in as expected. Without the right support, you could be left homeless between ending your current tenancy and exchanging on your home.
Finances: Manage Short & Long-Term Matters
Keeping your finances in good health should be a priority throughout the process. When thinking about the costs, you need to look beyond the purchase and legal fees. The logistics of moving and issues like redecorating should be accounted for. Crucially, you should always research mortgage rates and deals to get the very best outcome for your situation.
When looking at properties, it can be worth focusing on fixer-uppers or homes with growth opportunities. It shouldn’t necessarily be the driving factor of your decision. Still, long-term financial prospects make life far less stressful. You should not underestimate its impact.
Preparation: Know What You Need
Finally, the process can become stressful when it feels like you’re taking forever to find the right home. You can make life a lot easier on yourself by conducting advanced research in advance. A clear list of your non-negotiables and desirable extras will narrow your search. This can include the location as well as property features. After all, this will impact your lifestyle.
A little preparation goes a long way to helping you find the home of your dreams. Not least because the wrong choices can be ruled out far sooner. And when you are able to enter this environment with confidence, stress levels will naturally fall.
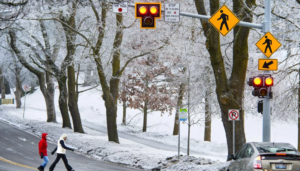
Image of Grand Blvd in Spokane
Even thinking about moving already causes stress and anxiety, because most often something unpleasant happens during this process. Something can break, someone can forget something, or someone can be late — there are many possible scenarios. That is why city residents, when changing their address, increasingly choose a Spokane moving service as a way to save time, nerves, and property.
This is actually a great idea, because professional services take care of the most difficult stages of the move and allow you to focus on more important moments.
What other advantages does Spokane moving service offer
People often choose to move on their own because it seems cheaper. In reality, such a decision can turn out to be more expensive, as it requires many resources and carries the risk of damage to belongings (especially expensive ones).
So what are you paying professionals for? Spokane moving service provides safe packing of belongings, proper loading and unloading, strict adherence to the schedule, and minimizes your physical effort. This approach truly simplifies the process and reduces the number of unexpected situations.
Moving service Spokane WA for comfortable moves
Moving in suburban areas has its own specifics — larger houses, more furniture, appliances, and expensive or fragile items. Moving service Spokane WA is often ordered for full process support, because it is about comfort, saving time, and often saving money.
Services usually include:
- packing and labeling boxes
- transportation of furniture and household appliances
- careful placement of items in the new space
In this case, packing and unpacking are done by professionals with extensive experience, who know how to do it properly to avoid damaging any details.
Commercial moving service Spokane WA for businesses
Commercial moves are often associated with large volumes of bulky equipment and furniture. Commercial moving service Spokane WA can offer different crew sizes and vehicle options so that the move is fast and comfortable.
Professional services take into account the type of commercial space, safety requirements, timelines, and stages of the move.
Office moving service Spokane WA: when time matters
An office move is about clear process organization, because every hour of downtime costs a business money. Office moving service Spokane WA usually saves businesses a lot of time and eliminates unnecessary headaches.
Teams know what to do in order to:
- avoid damaging equipment and documents
- minimize work interruptions
- preserve the logic of workspace layout
How to choose a reliable moving service
When moving, it is important to choose a company that fits not only in terms of price, but also by other criteria. Here is what we recommend paying attention to.
| Criterion | Why it matters |
| Work experience | Guarantees professional move organization without damage to belongings or unexpected situations. |
| Insurance | Property protection means safe packing, transportation, and the service’s responsibility for your belongings. |
| Clear schedule | Time control allows adherence to a clear schedule and helps avoid delays. |
| Real reviews | Customer trust is built through transparent company operations and real feedback from people who have already used the services. |
Moving service Spokane WA will not only help organize the process quickly and safely, but will also make moving day a pleasant memory rather than a terribly stressful day.
Purchasing a pre-owned vehicle involves more than selecting the right model. Understanding the financial commitment ahead of time is equally important. A digital EMI calculator gives borrowers a trustworthy estimate of their monthly repayment obligations before they submit a formal application.
Why do you need a digital EMI calculator?
Manual loan repayment calculation comes with several drawbacks:
- Requires applying the standard amortisation formula involving the principal, the monthly interest rate, and the number of instalments
- Time-consuming and effort-intensive
- Prone to human error
- Does not easily account for tenure variations
A digital used car loan EMI calculator eliminates these inefficiencies:
- Processes principal, interest rate, and tenure instantly
- Displays estimated EMI, total interest payable, and overall repayment amount within seconds
- Helps borrowers assess whether a loan structure fits their monthly budget, without any commitment
3 essential inputs required for accurate estimates
Accurate EMI estimates depend on three core inputs:
- Principal Amount: The total loan amount the borrower intends to avail, which can range from ₹1 lakh to ₹2 crore, depending on eligibility. A higher principal results in a proportionally higher EMI.
- Interest Rate: The annual rate applied to the outstanding principal. For used car loans, rates usually begin at 11.99% p.a. and vary based on the borrower’s profile. Even a marginal difference in rate has a measurable impact on total interest outgo over longer tenures.
- Tenure: The duration over which the loan will be repaid, which can range from 11 to 84 months. A longer tenure reduces the monthly EMI but increases the total interest paid; a shorter tenure does the opposite.
Benefits of early EMI estimation
Estimating the EMI before applying for a used car loan carries several practical advantages:
- Aligns monthly financial outgo with current income
- Prevents over-borrowing and ensures fast approvals
- Allows tenure optimisation based on repayment capacity, so borrowers can identify the most suitable loan structure for their financial position.
- Provides a clear view of the interest-to-principal split across the loan lifecycle
- Enables borrowers to compare loan offers across different rates and tenure combinations before committing
- Supports more informed discussions with lenders, as the borrower enters the process with a clear understanding of what they can repay
Early estimation also removes uncertainty from the application process. When the borrower already knows the expected EMI, the documentation and approval stages proceed with greater clarity.
How to use the IDFC FIRST Bank online calculator
The online calculator is structured for quick, error-free use. The following steps outline the process:
- Open the used car loan EMI calculator on the lender’s website
- Enter the desired loan amount
- Input the applicable interest rate, which is mostly communicated during the loan enquiry stage
- Select the preferred repayment tenure in months
- The calculator instantly displays the estimated EMI, total interest payable, and the overall repayment amount
The calculator offers two additional advantages:
- No login needed: Results are generated in real time as inputs are adjusted, so borrowers can compare multiple scenarios within a single session without any registration
- Amortisation schedule: Shows how the principal and interest components shift across each instalment. In the early months, a larger share goes toward interest; over time, more goes toward reducing the outstanding principal
Reviewing this schedule gives borrowers a complete picture of their repayment timeline and total borrowing cost before they apply.
Conclusion
A used car loan EMI calculator is most effective when used early in the buying process, before shortlisting a vehicle or approaching a lender. Running a few scenarios by varying the loan amount, rate, and tenure takes only minutes but can meaningfully shape the financial decision ahead.
Borrowers who enter the application process with a clear sense of their EMI range are better positioned to negotiate terms, choose the right tenure, and commit to a loan they can comfortably repay.
Two individuals with similar income levels may get different personal loan offers depending on their profile and lender. Also, the same borrower can receive different loan amounts and interest rates across lenders. The reason for this is primarily the set of eligibility factors, that each lender evaluates differently. Learn how these offers are determined and how they influence your borrowing experience.
Effect of eligibility on personal loan offer
Eligibility pertains to more than qualifying for the loan. It also influences how much you can borrow and the interest rate you get. Here are the key factors evaluated before approving a loan offer:
- Age
Your age gives lenders an idea of your earning stage. Borrowers with more years of stable earnings have stronger eligibility as they can handle repayments comfortably.
- Credit score
A good credit score assures lenders of your creditworthiness. It shows your responsible borrowing behaviour to protect their risk interest. A score of 750 or higher is considered good for a personal loan. In case of FIRSTmoney, you can apply for a personal with a CIBIL score of 710+ for salaried.
- Monthly income
Income is a crucial eligibility factor as it directly influences your repayment capacity. A higher income may lead to approval of a larger loan amount.
- Employment or Business
A good income figure must be backed by a stable source. Thus, your employment or consistency of business is assessed. A steady job or business adds to your credibility as an applicant.
- Existing obligations
Your current EMIs, credit card dues, and other liabilities affect your borrowing capacity. Lower obligation means a better loan offer and vice versa. You can check how this works with a personal loan eligibility calculator.
Why do personal loan offers vary across lenders?
Every loan provider has their own lending strategy based on their internal lending policies and regulatory guidelines. Here is what shapes their decision:
- Internal policies
The credit assessment framework varies across lenders. Some are more flexible than others. This impacts the loan amount you can get. The process of loan approval also matters. For example, some lenders might offer a completely paperless process, whereas others might require paperwork.
- Promotional campaigns
Sometimes, lenders extend a better loan offer based on their limited-period campaigns to attract new borrowers. They may include a higher loan amount or lower interest rates and charges.
- How to get an appealing personal loan offer
Small improvements in your credit behaviour and borrowing choices can boost your personal loan application. Here are some of the ways to strengthen it for a better loan offer:
- Maintain a strong credit profile
Pay your EMIs and credit card bills on time and keep your credit utilisation under control. A good repayment record and low dependency on loans steadily improve your credit score.
- Borrow within your repayment comfort zone
Clearly define your borrowing needs and borrow only what is needed. Check if your expected amount aligns with your income and existing expenses.
- Compare lenders
Go through the loan terms on varied lending websites and choose a lender that offers a competitive interest rate along with benefits like lower fees, flexible repayment, faster approval, and quick disbursal.
- Select loan tenure thoughtfully
Opt for a balanced tenure where you can manage the EMIs comfortably, while not increasing the interest outgo by stretching the repayment for too long.
- Negotiate
If you are applying with your existing bank, check if you can get better terms based on your existing relationship. Build your case based on your eligibility assessment with a personal loan eligibility calculator.
Final words
Different loan offers are a reminder that borrowing is not a standard process. Your eligibility is based on your financial habits, income, and credit profile, which shapes your personalised loan terms. So, it helps to consider how much you qualify for to get the right estimate. This understanding allows you to plan your application better. Take the step to smart borrowing today by checking your personal loan eligibility!

UPI has become the default payment method for millions of Indians, from street vendors to large retailers. Almost every transaction is now carried out through UPI. So much so that going wallet-free has become a reality. QR codes facilitate swift payments at POS terminals and UPI IDs for simple online transactions. Many banks fulfil this vision with RuPay Credit Cards. Learn everything about these UPI-powered options in this blog.
Benefits of a UPI-linked credit card
The UPI-linked RuPay Credit Cards make transacting feel quicker and hassle-free. Some of the many advantages include:
- Secured transactions
You are required to authorise every payment made through UPI. The system links your bank account with a one-time setup and encrypts your financial information for online security.
- Rewards for every spend
UPI-linked credit cards earn reward points on eligible transactions, adding value to your everyday payments. This, coupled with credit card rewards, adds to your savings on regular transactions.
- Widespread acceptance
UPI is widely accepted across retail and online merchants, making it one of the most versatile payment methods in India. Whether it is through scanning a QR code or paying through your UPI ID, you can select the option anywhere.
- Two-step payments
When you make a UPI payment, you are prompted with complete details about the amount and the recipient. This, coupled with a secure PIN, reduces the chances of unauthorised transactions.
- Simple registration
Right from obtaining the UPI-enabled RuPay Credit Card from IDFC FIRST Bank to linking it to a UPI app, the process is smooth and quick. Make sure to check the eligibility to breeze through the online credit card application.
How do UPI-linked credit cards work
Using a UPI-linked credit card is similar to transacting with funds in your bank account. The mechanism follows the same framework, including these steps:
- Link your credit card to the UPI app
Add your UPI-enabled credit card to your preferred UPI app by selecting the option ‘Add Credit Card’ under the ‘Cards’ section. Add the last 6 digits and the expiry of the credit card.
- Set a UPI PIN
Set your 4 or 6-digit UPI PIN to securely approve every transaction. Choose a PIN that is not easily guessable and avoid sharing it with anyone.
- Make Payments
Start transacting based on your credit limit. Pay for regular expenses like utility bills, groceries, and subscriptions. For payments at merchant stores, pay through QR codes.
Key things to note about the UPI-linked feature
To truly enjoy the seamless experience of a UPI-linked credit card, pay attention to these crucial aspects before you initiate the credit card apply online process.
- Merchant payments only
UPI-linked credit cards work for merchant payments, not person-to-person transfers. For example, with a RuPay credit card from IDFC FIRST Bank linked to your UPI app, you can pay at merchant outlets across India by scanning their QR code through the app. However, you cannot use it to send money directly to another UPI user.
- Importance of secure networks
The credit card linked to UPI is typically digital. When you apply for the credit card online and make payments, it’s best to avoid public Wi-Fi to protect against data breaches. Safe habits go a long way in digital security.
- Credit limit applies
Your UPI spending is linked to your credit limit. So, it helps to separate your UPI spends with a credit card as opposed to how you make them against your bank account balance.
- Charges still apply
Much like regular card usage, standard charges apply based on usage, including interest on outstanding balances, late payment fees, and cash advance fees, based on the UPI-linked credit card usage.
- Transaction limits
The standard daily limits on the maximum amount and number of transactions applicable to UPI apps apply when you make payments through the UPI-linked credit card. Also, the daily limit is affected by your total credit card limit.
Final words
UPI-linked credit cards combine the instant payment system with flexible credit. You can continue paying for your everyday transactions with familiar convenience, while earning reward points against such payments. Every UPI transaction qualifies for varying reward points based on the transaction amount and the spending category. Track your payments to develop smarter spending strategies. You need not spend more than usual. Simply upgrade the way you spend to align with the rewards.