
Lifestyle planning is about creating a life that feels balanced, intentional, and sustainable. Many people associate planning with spreadsheets and numbers, but lifestyle planning goes far beyond that. It’s about understanding what you value most and building financial habits that support those priorities.
When done really well, lifestyle planning becomes a framework for how you live each day. It helps you make confident decisions about spending, saving, and even time management. It encourages you to stop reacting to life’s changes and start directing them.
Via Pexels
Knowing What You Want Is The Foundation
It’s easy to think that more money automatically means more happiness. But true lifestyle planning begins by asking what really matters to you. Is it travel, family time, career growth, or freedom from financial stress? Once you know what’s important, you can design your financial life to support it.
Start by defining your goals in concrete terms. Maybe it’s that you want to buy a home in five years or retire early enough to enjoy a second career in your later years. These goals give structure to your plan. They help you determine how much you need to earn, save, and invest, rather than simply guessing or copying someone else’s approach.
Balancing Dreams With Practical Steps
A well-designed plan doesn’t eliminate spontaneity (the plan shouldn’t steal all the joy); it creates room for it. The trick is balancing ambition with realism. You can’t expect to achieve financial independence overnight, but you can make steady progress toward the ultimate destination by aligning your daily actions with your long-term goals.
Tracking your expenses and adjusting when needed are all part of the process. Avoid overcommitting yourself financially, even for things that may seem harmless now. Living slightly below your means gives you the flexibility to handle unexpected changes without any anxiety. And it also allows you to say yes to opportunities that align with your values rather than obligations.
Building Security Into Your Plan
Financial security is often overlooked until it’s too late. But it’s one of the most important parts of lifestyle planning. Emergencies, health issues, or economic shifts can disrupt even the best-laid plans. That’s why building a cushion through savings and insurance is essential.
Consider setting aside at least three to six months of expenses in an emergency fund. This gives you peace of mind and prevents you from relying on credit when life surprises you. You may also want to explore estate planning to ensure your assets are protected and your loved ones are cared for. It’s not just for the wealthy; it’s a really great way to make sure your long-term plans stay intact no matter what happens.
The Reward Of Living Intentionally
The beauty of lifestyle planning is that it turns your financial choices into reflections of your values. It’s not about deprivation or restriction. It’s about clarity and confidence—as easy and as simple as that. When you understand what you want, and you’ve built the systems to support it, every purchase, investment, and experience feels purposeful.
You gain the freedom to enjoy life without guilt or worry because you know your choices fit within a bigger plan. And that’s the real goal: to create a lifestyle that feels rich in meaning, not just money.
In the world of real estate finance, there are two well-known ways for buyers to fund acquisitions:
1) Traditional Bank Loans
2) Hard Money Loans
Hard money loans are made primarily by private lending companies and individuals to real estate investors.
The term “hard money” refers to the fact that these loans are made based on the value of the property used as collateral rather than the creditworthiness of the borrower.
Various factors, such as market conditions, the financial strength of the borrower, and the condition of the property, will dictate which type of loan is most advantageous for your deal.
When to Use a Traditional Bank Loan
When is it advisable for a buyer to finance an acquisition using a conventional bank loan?
First, let’s consider the tone of the real estate market:
- Is the market overheated?
- Are sellers receiving multiple offers at or above their asking prices?
- Is there a scarcity of inventory?
If none of the above conditions exist, then the most sensible course of action is to secure financing from a bank.
Keep in mind, banks take substantially longer to approve and fund a loan than a typical hard money lender.
If market conditions are such that the speed of a transaction is not a concern, then using a commercial bank makes sense.
Using a traditional bank makes for a successful transaction, provided the borrower can satisfy the bank’s rigorous lending standards. The credit score of an ideal borrower is important, as is the type of real estate project and the borrower’s debt-to-income ratio.
It is advisable to use a bank with which the borrower has an existing relationship. If the bank knows the borrower and the borrower knows the bank, the chances of having a successful transaction are high.
When to Use a Hard Money Loan
If the real estate market is overheated and buyers outnumber sellers by a wide margin, a real estate investor could consider using hard money instead.
A hard money loan can free up the investor to make an all-cash offer and could be the difference between completing a transaction and losing out to another buyer.
1- Speed of Funding
With a traditional bank loan, the process from start to finish usually takes several weeks or even months.
In contrast, a hard money loan can be funded in less than a week because there is less reliance on the borrower’s financial history.
This ability to fund quickly is the principal advantage of a hard money loan.
2 – Distressed Property Acquisition
The second advantage of a hard money loan arises when the borrower is purchasing a distressed property.
If the property is in poor condition and requires a major rehab, it might not qualify for a conventional loan.
In that case, the borrower can still obtain financing via a hard money loan.
Once the property has been renovated, the borrower refinances out of the hard money loan and into a traditional bank loan.
3 – Fix-N-Flip Projects
The third advantage of using a hard money loan is when the transaction is a fix-and-flip project.
Such projects are of short duration, ranging from several weeks to a few months. There is a timeline, a clear estimate of the cost of the project, and a realistic plan to market and sell the property.
To qualify for a fix-n-flip loan, most hard money lenders will require the borrower to have experience in this field. Getting funding for your first fix-and-flip project will be challenging if you do not have experience or a partner with a successful track record.
4 – Customizable Terms
Last but not least, the terms of a hard money loan are often tailored to the specific needs of the borrower.
The loans can be interest-only, have flexible payment schedules, and have lower loan-to-value ratios. For many fix-and-flip projects, cash flow is a primary concern, and having flexibility with respect to terms is important.
For more background on hard money, check out the complete guide.
What to Watch Out for With Hard Money
What should a buyer be aware of when deciding whether or not to obtain a hard money loan?
1 – Higher Costs
First and foremost are the higher costs associated with hard money loans.
The interest rate on a typical hard money loan can be three or four percentage points higher than on a traditional bank loan.
2 – Clear Exit-Strategy
Second, the buyer must have a clear and viable exit strategy that is realistic and accounts for possible changes in market conditions, such as an increase in interest rates causing demand to plummet or an influx of new construction in the proximity of the property.
3 – Avoid Being Over-leveraged
Third, the borrower must avoid being debt-heavy.
Investors must not be over-leveraged. Being over-leveraged could lead to a default and the loss of whatever equity the borrower contributed to the project.
4 – Scammers
Working with a bank also allows the borrower to avoid various pitfalls inherent in the practices of some hard money lenders.
A few hard money lenders offer terms that are so favorable they outshine all other lenders (including banks) by a considerable margin.
In this case, you can be almost certain the deal is most likely a scam.
Watch out for terms that include an interest rate that is below market rates or for lenders who ask for fees to be paid before borrowers receive funding.
If the lender does not require collateral and is willing to lend an amount equal to one hundred percent of the value of the property, back away and move on.
No successful hard money lender with their salt will ever offer a 100% loan-to-value ratio.
Also, watch out for lenders who try to change the terms of a loan just prior to closing or after closing.
Perhaps the clearest sign that a scam is in the works is if the hard money lender asks for an upfront fee to get the loan process started.
The fee can be a small amount, such as $4,000 or $5,000. Unfortunately, the loan is never funded and the borrower is out the amount of the fee.
For more background on hard money scams, check out the following guide.
In Conclusion
Choosing between a traditional bank loan and a hard money loan will ultimately depend on your goals, timing, and the particular conditions of the deal.
If time is on your side, you have strong credit, and the property is in good condition, a conventional bank loan will offer lower costs and more favorable terms.
However, when attractive opportunities arise in competitive real estate markets for distressed property acquisitions, or short-term fix-and-flip projects the speed, flexibility, and creative financing features of hard money loans can be an invaluable tool.
The key is understanding when and how to use each option.
Hard money loans reward investors with a clear exit strategy, local knowledge of the housing market, and a conservative approach to taking on leverage.
When used strategically and with proven lenders, hard money loans can capitalize on opportunities that traditional financing simply can’t match.
Your financial advisor is someone whom you trust to have your best interests at heart. When they act dishonestly, it can cost you more than dollars and cents. Financial advisors often prey on first-time investors and older people, but even seasoned investors can sometimes fall victim.
When scams happen, they often deprive individuals and families of years, if not a lifetime, of hard-earned savings. A scam may even cause some to lose faith in the financial system, leading them to miss out on legitimate opportunities to build wealth.
Dishonest financial advisors aren’t always easy to spot, but there are a few common signs you can look out for in order to protect yourself.
1. Overpromising Returns
Guaranteed high returns with little or no risk simply do not exist in the market. Generally, the higher the returns, the more risk an investment endeavor involves. Anyone who promises you the opposite is likely attempting to take advantage of your inexperience in investing or your trust in them. If someone pitches you a “zero risk” or “can’t lose” investment, do not believe them.
2. Obscuring Fees
Mutual funds, ETFs, or soft dollar arrangements all can involve unclear commissions and high management fees. Advising you to swap out your life insurance policy for a new and unnecessary one (“churning”) is another area where your financial advisor is likely receiving a hefty commission in exchange for their recommendation. All of these are examples of obscured fees. These costs can not only add up but also put your larger portfolio at risk. When your investments are tied up with high trading costs, proprietary funds, and commission-driven options, your investment advisor has a powerful incentive to recommend investments to you that may not suit your needs.
3. Pressuring You Into Decisions
Your advisor may be the expert, but they should still allow time for you to do your own research and reflect on an investment opportunity. When advisors push clients to act quickly, they may be attempting to cover up a scam or access your funds quickly to correct their own mistake. If you are being pressured into making a decision by your financial advisor, report it to their firm or manager.
4. Avoiding Written Documentation
Advisors who refuse to provide written agreements or confirmations are usually hiding something. A registered security should come with an extensive paper trail, including a prospectus, annual reports, SEC filings, and audited financial statements. If your advisor is recommending unregistered securities or other risky investments, they may attempt to avoid putting the details in writing. Always ask for the terms and conditions of your investment as an explicit document, instead of a phone call or handshake agreement.
5. Overly Complicated Explanations
While the market is complicated, advisors who rely on jargon or convoluted explanations may be obscuring important information on purpose. Additionally, not every investment opportunity is suitable for the average investor. If your advisor is recommending more complex strategies for your portfolio, like derivatives, Forex, or cryptocurrencies, take the time to examine why they are recommending only strategies that you are less likely to understand. If you are not sure where your money is going, do not invest.
6. Questionable Credentials or Licensing
Check your broker registration with FINRA and state licensing boards to ensure that your financial advisor is legitimate. Verifying their credentials is not only good practice, but you may turn up records of past scams or significant losses of which you were not previously aware.
7. “Exclusive” or Secretive Opportunities
Advisors promoting limited-access or secretive investments without full transparency are most often bad actors. While everyone wants to be cut in on the best deal, your financial advisor should only recommend aboveboard opportunities for your portfolio. Secretive opportunities like prime bank programs, access to private trading platforms, or “proprietary” investment formulas tend to be nothing more than ways for a fraudulent financial advisor to avoid sharing details that would make you realize the opportunity is a scam. By presenting an offer as exclusive, advisors can manufacture a sense of urgency or obligation that pushes clients to say yes.
Protect Yourself and Your Investments
As the age-old saying goes, “If it’s too good to be true, it likely isn’t.” Investment inherently involves some degree of risk. Stay vigilant and trust your instincts if you think that you are being offered a scam by even a trusted financial professional.
Unfortunately, some scam artists go to great lengths to obscure their fraudulent actions, and even the most careful investors may not realize they’ve been deceived until it’s too late. If you suspect that you have suffered losses due to a dishonest financial advisor, you may still have options to recover your funds. Contact an investment fraud lawyer to learn whether you may be able to file a FINRA arbitration claim or lawsuit.
Families often discover in moments of crisis that the hardest challenge is not grief but uncertainty. Without written instructions, even small choices can become sources of conflict, while the pressure of dividing property or deciding care multiplies stress. Legal documents such as wills, advance directives, and powers of attorney shift that responsibility from debate to clarity, guiding relatives with confidence.
What once felt like a private topic is now entering daily conversations about elder care and financial security. Preparing a will signals more than organization—it shows foresight and care. A single document can prevent disputes, preserve family trust, and offer peace of mind. Beginning today with even one step lays a foundation for steadier decisions tomorrow.
Why Wills Provide Clarity in Everyday Choices
When urgency collides with emotion, a will provides a calm point of reference. It distributes property, names guardians, and records care preferences in precise terms. This guidance spares families from uncertainty, reduces disputes, and shifts focus from argument to honoring wishes. Clear direction offers reassurance when time is short and decisions cannot wait.
The strongest wills also capture details that extend beyond money. They note decision contacts, provide account summaries, and record gifts of sentimental belongings often overlooked. Even simple choices, such as who receives a cherished photo or which flowers will rest near a casket, can be clarified with compassion. Such touches prevent misunderstandings and turn potential conflicts into moments of understanding. Instead of piecing together intentions, relatives can carry out responsibilities with clarity, confidence, and respect.
Essential Documents That Support Family Decisions
A will lays the groundwork, but it gains strength when paired with complementary documents. Trusts can streamline settlements, while retirement and insurance accounts transfer more smoothly when beneficiaries are clearly named. Digital access lists—covering usernames, passwords, and key account details—close gaps that might otherwise stall financial management. Together, these resources form a complete system that allows families to act decisively rather than struggle with delays.
Organization and security are just as important as the documents themselves. Originals belong in a safe-deposit box, while accessible copies should be kept with both legal counsel and a trusted family contact. A concise, labeled index—maintained in both physical and digital formats—turns scattered papers into an orderly, reliable reference.
How Wills Simplify Family Financial Matters
An executor flipping through a labeled folder of bank statements, mortgage papers and credit notices finds decisions far easier when a will maps ownership and debt responsibility. A well-written will lists debts to be paid, names recipients for accounts and items, and clarifies whether joint assets pass by title or instruction, reducing arguments over who owes what. Noting taxes and distribution timing sets clear expectations.
When liabilities and assets are listed together, heirs see net value, avoid surprise bills, and can prioritize necessary payments instead of guessing. A one-page liabilities and asset summary kept with the will serves as the fastest reference for family and advisors going forward.

Communication That Turns Planning Into Action
Legal papers provide structure, but conversations give them meaning. A family gathered around the dining table with documents in hand discovers not only what the plans say but how they will work in practice. Designating a single point of contact, updating copies so they remain current, and clearly stating care and legacy preferences turn a static file into a living plan that guides real decisions.
Small practice exercises make this guidance tangible. Walking through the process of paying bills, contacting banks, or reaching advisors reveals gaps before they become urgent problems. Pairing an annual review with a short family discussion keeps information accurate, strengthens cooperation, and turns plans into dependable action.
First Steps Families Can Take Right Away
Starting estate planning may feel overwhelming, but breaking it into simple steps makes the process approachable. Begin with a small folder labeled for originals and another for working copies. Place wills, deeds, insurance papers, and recent account statements inside, then create a brief checklist naming contacts and initial responsibilities. This structure provides clarity when someone needs to act quickly.
Work in short, manageable sessions of 20 to 30 minutes to avoid fatigue. Once gathered, store originals securely, keep digital backups encrypted, and share access details with one trusted relative and your legal adviser. A yearly 30-minute update of names, beneficiaries, and account details prevents outdated information from causing unnecessary complications.
Wills and related legal documents turn difficult choices into clear, manageable actions during stressful times. They assign property, outline financial obligations, and record personal preferences so families act with certainty instead of hesitation. Regular reviews keep details accurate, while open conversations turn written words into living guidance that relatives can follow with confidence. Preparing these documents is not only a matter of protecting assets but also an act of compassion that reduces conflict and strengthens trust. Beginning with a single will today creates order, stability, and peace of mind that will support loved ones when guidance matters most.
If you’ve been thinking, “how can I sell my house fast?”, one of the best ways to get buyers interested is by staging your home properly. Staging means preparing your property so it looks its absolute best for viewings, helping it sell quicker and often for a higher price. When done right, it can completely change how people feel when they walk through the door. The key is to be thoughtful about every detail and make improvements that show off your home’s full potential. Here are a few ways to do that and make sure your place stands out from the competition.
https://www.pexels.com/photo/property-with-red-and-white-home-for-sale-signage-8469934/
Declutter but Don’t Depersonalise
Start by clearing out any clutter that’s built up over time. Garages, cupboards, and spare rooms are usually the worst offenders. Buyers need to see the space, not your belongings. If you’ve got too much stuff, consider putting it into storage or giving a few things away. Removing bulky furniture and swapping it for smaller pieces can also help rooms look more spacious. The goal is to create a clean, open environment that still feels lived in but allows buyers to picture themselves living there.
New Paint
A fresh coat of paint can completely transform your home. Light, neutral colours make rooms look bigger and brighter, which is exactly what buyers want to see. If you’ve got bold colours on the walls, (think purple, red, or lime green) it’s worth toning them down. Most people want something move-in ready, not a decorating project. Even repainting your front door can make a big difference to your home’s overall feel. Little touches like this make your property look cared for and instantly more appealing.
Fix and Clean
Don’t overlook the small things. Loose handles, cracked tiles, or marks on walls might not bother you, but buyers notice them straight away. Fixing these details helps give the impression that the home has been well maintained. Once repairs are done, give the whole place a deep clean. Polish floors, scrub bathrooms, and get rid of any lingering smells. The cleaner your home looks and feels, the easier it is for viewers to imagine themselves living there.
Tidy the Garden
Your outdoor space plays a bigger role than you might think. Even if it’s small, a tidy garden can make a big impact. Cut back overgrown plants, mow the lawn, and clean up any outdoor furniture. Wash the patio and clear away debris to make it feel fresh and welcoming. It might not directly add value, but it definitely helps your property make a good impression, and that can be the deciding factor for buyers.
Update your Kitchen
The kitchen is one of the most important rooms in any home and can make or break a sale. You don’t have to spend a fortune to make it shine. Refacing cabinets instead of replacing them can give the room a brand-new look for a fraction of the cost. Updating countertops can be pricier but often adds solid value to your home. Even small improvements like new handles, lighting, or a modern backsplash can make the kitchen feel updated and inviting.
The landscape of personal finance blogging has dramatically evolved. One vital aspect that can set a blog apart is visual branding. With the plethora of information available online, capturing attention is more challenging than ever.
Compelling visuals can make the difference between a reader swiftly scrolling past your content or stopping to engage with it. By focusing on visual branding, financial bloggers can enhance communication, improve engagement, and create a more memorable experience for their audience.
This article delves into the impact of compelling visuals for personal finance content, helping bloggers improve engagement and communication.
Why Visual Branding Matters
Visual branding refers to the use of images, colors, typography, and overall design to create a distinct identity for a blog. In the realm of personal finance, where topics can often be dry or complex, effective visual branding brings a critical edge.
Visuals are processed faster than text. This makes it essential for bloggers to adopt techniques that emphasize their content visually.
Not only does visual branding attract readers, but it also fosters trust and establishes authority. A polished and cohesive design reflects professionalism.
Creating Consistency
One key benefit of visual branding is the ability to create consistency across a blog’s various elements. A well-defined color palette, consistent fonts, and cohesive imagery can help establish a recognizable brand identity.
For personal finance bloggers, this consistency encourages deeper connections with audiences. This is because readers often return to familiar and visually appealing content.
Enhancing User Experience
The way readers experience your blog is important for keeping them interested and encouraging them to interact. Visuals like infographics, charts, and images can help make even tricky financial information easier to understand.
For example, an infographic that shows key budget tips can catch readers’ attention much more than a long text post. Plus, adding images or charts can break up lots of text.
Building Trust and Authority
Visual branding can help make your personal finance blog look more trustworthy. When your blog looks polished and professional, readers are more likely to believe that you know what you’re talking about. This trust can lead to more people visiting and engaging with your content.
Having a professional look for your blog is important because it helps build trust with your readers, especially for personal finance topics. This trust is key for getting readers to come back and explore more of your content.
Elements of Effective Visual Branding
When creating the visual branding for a personal finance blog, there are several important things to think about.
First, the color palette is key. Colors can make people feel certain emotions. This means choosing the right colors that match the blog’s message can help connect with readers.
Next, the logo is really important. A good logo should be easy to recognize and should show what the blog is all about. It represents the blog’s values and makes it stand out.
Typography, or the choice of fonts, is also important. The fonts should be easy to read, but they should also match the blog’s style and personality.
Using images like infographics, charts, and pictures can help explain complicated topics in a simple way. Good visuals keep readers interested and help them understand the content better.
Finally, consistency is key. Using different styles for each post can confuse readers. Keeping a consistent style throughout the blog helps make the brand feel clear and trustworthy.
Implementing Visual Branding Strategies
Building a strong visual brand takes some planning and thought. Here are some steps you can follow to create a great visual brand for your blog:
First, you need to define your brand identity. Think about what makes your blog different from others. Consider your blog’s topic, who your readers are, and the message you want to share with them.
Next, once you know what your blog is all about, it’s time to design the visual parts, like the logo or banner. You can create a banner online that matches the style and look of your blog.
Finally, make sure to produce consistent content. Keep all your visuals, like images and logos, in line with your brand’s style. Regularly updating your visual content will help your readers recognize your blog easily and build a stronger connection with them.
Leveraging Infographics in Personal Finance Blogs
Infographics are a powerful way to present data visually. They can depict statistics, process explanations, or comparisons in a compact format that attracts readers.
Infographics are liked and shared on social media three times more than other content types. This makes them a must-have for bloggers.
Using infographics the right way is important for making your blog stand out. Here are some key tips:
First, make sure your messaging is clear. The goal of an infographic is to teach your readers something, but you don’t want to give them too much information at once. Keep it simple and easy to understand.
Next, remember to include your blog’s logo and use the same colors you always use. This helps reinforce your blog’s brand and makes your infographics instantly recognizable to your readers.
Lastly, make sure your infographics are optimized for search engines. Use alt tags and the right keywords so people can easily find your infographic when searching online. This helps your blog reach more people.
Emotional Appeal Through Visual Storytelling
Visual branding can transcend basic aesthetics to create emotional connections with readers. Storytelling through visuals captures attention and showcases the human side of finance. This is a topic often seen as purely numerical.
Use real-life examples, testimonials, and relatable imagery to build connections with your audience.
Successful visual storytelling can help your blog in many ways. First, it can increase engagement.
When readers feel an emotional connection to your content, they are more likely to share it with others. This helps your blog reach more people.
Second, visual storytelling can build brand loyalty. When people connect with your images and messages, it creates memorable experiences that make them want to come back to your blog again and again. This loyalty helps your blog grow over time.
Elevating Your Blog with Visual Branding
Visual branding plays a pivotal role in the success of personal finance blogs. By focusing on elements such as color palettes, logos, typography, and effective imagery, bloggers can enhance communication and engagement with their audience. As the digital landscape continues to evolve, embracing visual branding not only builds credibility but also fosters lasting connections with readers.
To stand out in the crowded field of finance blogging, it’s time to invest in your visual branding strategy.
For more poster tips, check out our blog posts.
There’s no smarter way to build wealth than investing your money. Take your cash and put it in assets that will grow in value over time. It’s not rocket science – and the right approach can easily help you turn a small fortune into a much larger one.
Unfortunately, there’s an aspect of investing that’s sometimes hard to ignore: its unethical nature. Some of the best-performing investments involve pumping money into oil or gas companies, weapons manufacturers, and so on. It can leave a sour taste in your mouth and almost taint your earnings, though there could be a solution on the horizon.
This is where we’re going to introduce the idea of ethical investing. It’s something of a trending word in the finance world, but what does it mean – and is it even possible to invest money ethically and still see returns? Let’s find out!
What is ethical investing?
Ethical investing is when you invest money in things that don’t have a negative impact on the planet, societies, individuals, etc. Your money goes into companies or concepts that have either a neutral or positive impact. An ethical investment firm can help you identify opportunities like this – and the good firms will let you explain your ethical standings and specifically avoid investments that go against what you believe in.
Is ethical investing actually possible?
Yes! You’ll be surprised how many things in the world are actually quite ethical and will generate good short or long-term returns. Renewable energy is the clearest example of this. It’s a fantastic alternative to putting money into oil and gas companies – and history shows that renewable energy investments will keep growing with time.
Will ethical investments be a better choice for my money?
The answer to this depends on you and your morals. Some people don’t have a problem investing in various companies or funds, as long as they generate money over time. That’s completely your prerogative, and nobody should shame you for that.
On the other hand, if you feel uneasy about some of the investment opportunities out there and would rather put money in things that help you do good, then ethical investments will be an obvious improvement for you specifically. You can spend money, but have peace of mind knowing that you’re not causing a negative impact.
As for whether or not it’s smarter from a strictly financial sense, the jury’s still out. Some ethical investments are extremely profitable while others are not. You also give yourself a smaller pool of investment opportunities to choose from, which can limit your diversity. It all comes down to your investment goals and how much you care about what you’re investing in.
In conclusion, ethical investing is an alternative way of spending your money and trying to develop wealth. It gives you chances to invest in funds or assets that don’t have a negative real-world impact and are more likely to have a positive one. You can absolutely make money this way, but it might take a bit longer and be slightly harder to identify the right investment opportunities.
Losing a loved one is never easy. However, the dearly departed did not want financial worries to be another cause of stress at this difficult time. This was their intention when leaving a property to you. As the beneficiary, though, it could potentially introduce new headaches altogether. And not only because other relatives might try to contest the estate.
The process of navigating through the legal and administrative red tape of inheritance can be lengthy and complicated. So, to prevent issues as much as possible, you want to work with a probate attorney who can handle the process on your behalf, reducing the risk of conflicts and missed deadlines. This can also ease potential challenges that may arise with other relatives.
Ultimately, you can’t worry about upsetting them. After all, your lost loved one clearly stated their intention for you to inherit the property. Still, knowing what to do with it isn’t always easy, especially as there is no one-size-fits-all solution. Here are three of the best options to consider.
Sell It
Leaving the property to you is a lovely gesture. In reality, though, it’s not just an asset. It’s a potential liability. Ownership can impact your taxes while maintaining the property could be an issue for your cashflow. With this in mind, the best option may be to sell the property. Not least if it is located a long way from where you live.
Similarly, you may find that the repair costs are beyond your budget, which makes selling the most practical choice. Traditional selling may not be possible due to the condition of the home. Or it may be a property that would take many months to sell. With the home buyer, PDX Renovations, it is possible to get a cash offer and sell within days. It is often a superior choice.
Aside from a cash offer, home buyer companies can offer alternative solutions. Either way, relinquishing the asset in this way is a quick route to funds before the situation becomes a nightmare.
Live In It
If you have inherited the family home, it might be that your loved one wants you to live in it. This may be the case if you have yet to purchase a home of your own or had plans to return to your hometown. This could be the start of a new chapter for you while simultaneously continuing your family’s legacy.
However, it should be noted that the property might need more than a little TLC. Learning essential homeowner skills can equip you with the ability to complete many of the upgrades yourself. This will save both time and money. You can also look to add character through small personal touches like adding new family photos or celebrating your passions.
Modernization can occur with new window installations, erecting a garden room, or creating a home office space. Many of these tasks deliver positive ROIS. They also strike a balance between family tradition and your personal tastes.
Rent It
Alternatively, you may want to retain the asset without living in it. You would then have a property that could be passed onto your children in later life. Or an asset that could be sold should you ever encounter financial difficulties. Still, you will want to do something with it in the meantime. Renting it out could be the best solution.
With Airbnb property manager finders AirDNA, you can find a team to manage short-term bookings. This allows you to tap into the financial rewards of short-term tenancy for holidaymakers and business folk with a backseat role. This creates a secondary source of income that will transform your life for the better.
Or you could seek a simpler and more stable income by becoming a traditional landlord. A long-term tenant will give you a monthly renting fee. Again, it’s a revenue stream while the value of the asset continues to grow.
Top 7 Benefits of Outsourced Paraplanning Services for Financial Planners
As a financial planner, your day is filled with client meetings, investment strategies, portfolio reviews, and keeping up with an ever-changing regulatory landscape. But there’s a part of your practice that often gets pushed aside: the technical, time-consuming work of paraplanning. That’s where outsourced paraplanning services come into play, a growing solution that’s helping financial planners improve efficiency, reduce costs, and maintain high service standards.
If you’ve ever wondered whether outsourcing your paraplanning is right for you, read on. Here are the top 7 benefits of outsourced paraplanning services and why more financial planners are making the switch.
What Is Outsourced Paraplanning?
Simply put, outsourced paraplanning services involve hiring external experts to handle the technical and administrative tasks of preparing financial plans, reports, and compliance documentation. Instead of having a paraplanner on your in-house team, you partner with a specialized service provider who delivers high-quality, accurate paraplanning work on demand.
These services include research, preparing recommendations, financial modeling, fact-finding document analysis, and ensuring compliance with the latest regulations. The key benefit? You get expert paraplanner support without the cost and complexity of managing another full-time employee.
If you’ve ever wondered whether outsourcing your paraplanning is right for you, read on. Here are the top 7 benefits of outsourced paraplanning services and why more financial planners are making the switch.
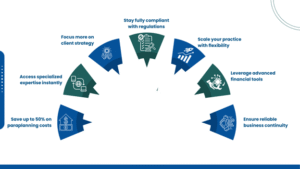
1. Cost Efficiency: Pay for What You Use
Hiring a full-time, in-house paraplanner comes with more than just a salary. There are recruitment costs, employee benefits, training, and office space to consider. With outsourced paraplanning services, you pay only for what you need, whether it’s a few reports a month or a full-time equivalent workload.
The outsourced paraplanning costs are generally much lower compared to the total expenses of an in-house paraplanner. This helps smaller firms or solo financial planners manage their budgets better without compromising on the quality of service.
2. Access to Specialised Expertise
It’s unrealistic to expect every financial planner to have deep technical paraplanning expertise. Fortunately, outsourced providers employ paraplanners who specialise in areas such as investment analysis, tax structuring, insurance review, risk profiling, and compliance research.
This means your clients get high-quality, in-depth reports and recommendations without you needing to spend hours doing detailed calculations or regulatory research yourself. The paraplanner support you get is often from professionals who have worked across multiple industries, bringing valuable insights and technical rigor that would be hard to replicate in-house.
3. Free Up Time to Focus on Strategic Advice
Let’s face it, most financial planners got into the business to help clients achieve their financial goals, not to spend hours drafting technical reports or researching the latest compliance regulations. Outsourcing paraplanning frees up your time so you can focus on strategic advice and building meaningful client relationships.
Rather than juggling spreadsheets, fact-finding questionnaires, and investment research, your time is spent where it matters most, growing your business and deepening client trust.
4. Better Compliance and Consistency
In today’s highly regulated environment, staying on top of compliance is non-negotiable. With paraplanning compliance constantly evolving, relying solely on internal resources can expose your business to compliance risks. Many firms find that paraplanning outsourcing is the best way to keep up with these constant changes.
By using outsourced paraplanning services, you gain access to experts who are always up-to-date with industry regulations, such as ASIC compliance in Australia or other local regulatory frameworks. This ensures your reports, recommendations, and documentation meet the highest quality and compliance standards, reducing the risk of costly mistakes or audits.
5. Scalability and Business Flexibility
Financial planning practices aren’t static. Some months are busier than others, especially during tax season or market volatility. Paraplanning services offer the flexibility to scale up or down based on your workload without the hassle of hiring or laying off staff.
Whether you need financial planning support for a few complex cases or consistent paraplanning help every week, outsourcing allows you to match your service level with your business cycle. This kind of flexibility is hard to achieve with an in-house team.
6. Leverage Advanced Technology
Top outsourced paraplanning providers use sophisticated financial modeling, risk analysis, and reporting tools that most small advisory firms wouldn’t invest in directly. These technologies automate repetitive tasks, speed up calculations, and help generate professional, consistent reports quickly.
This means your paraplanning output is not only faster but also more accurate and reliable. You get the benefit of advanced tools without having to invest in expensive software yourself, keeping your practice competitive in a tech-driven world.
7. Reliable Business Continuity and Peace of Mind
What happens if your in-house paraplanner suddenly leaves or falls sick? Business continuity can be a real challenge for small financial planning firms.
With outsourced paraplanning services, there’s no disruption to your workflow. Most service providers operate under strong Service Level Agreements (SLAs) and guarantee timely delivery of work, ensuring your business remains fully operational at all times.
Conclusion: Is Outsourced Paraplanning Right for Your Practice?
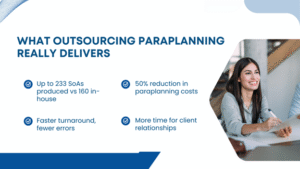
The paraplanning benefits are clear cost savings, access to expertise, improved compliance, time efficiency, scalability, advanced technology, and reliable business continuity. By outsourcing paraplanning, you gain a flexible and professional solution that helps you deliver higher-value advice to your clients without the burden of managing every technical detail in-house.
If you’re aiming to focus more on client strategy, grow your practice without adding overheads, and stay compliant in a changing regulatory landscape, it’s time to consider partnering with a reliable outsourced paraplanning provider.
Institutions don’t just set the stage for daily life — they shape the conditions where safety can either thrive or collapse. When misconduct occurs, attention often stops at an individual name. Yet schools, hospitals, corporations and agencies make choices about staffing, oversight and response that directly affect vulnerability, accountability and long-term trust across communities.
Examining these organizational layers uncovers how preventable harm takes root. Patterns of weak hiring practices, ignored complaints, or neglected safety logs often point to systemic choices rather than isolated missteps. Holding institutions responsible broadens the scope of justice: it recognizes how policies and failures of oversight create risks that outlast any single offender’s actions.
When Institutions Shape Risk Environments
Safety lapses often grow from overlooked details rather than dramatic failures. A skipped reference check, a rushed orientation or too few supervisors on duty each increase the chance that misconduct slips by unnoticed. Looking closely at hiring standards and training design often reveals how everyday decisions created risks long before harm was reported.
Personnel records, complaint logs and training rosters often highlight the same recurring shortcuts: temporary hires brought on without vetting, shallow one-off trainings presented as compliance, and complaints filed but never pursued. These patterns show that risk emerges from deliberate choices, not accidents. Legal professionals like Dallas sex crimes attorneys often point to such oversight gaps as clear evidence of institutional responsibility.
Documenting Negligence That Goes Beyond Policy Failures
A maintenance checklist with blank boxes, a flickering corridor light and an unsigned safety log outweigh posted rules. Written protocols promise monthly checks and immediate reporting, while records show skipped dates, delayed repairs and incidents closed without inspection. Comparing procedures to timestamps, work orders and invoices exposes where practice diverged from policy.
Emails marked read without replies, audit memos that praise managers while incidents repeat, and safety walk reports filed long after problems were reported signal indifference. Cross-referencing timestamps, payroll for overtime, and vendor receipts can reveal systemic neglect. A dated folder with complaints, photos and follow-up logs often proves patterns for investigators.
Legal Pathways for Institutional Accountability
A stack of unprinted emails, a locked shared drive and a calendar full of ignored meetings often tell more than a policy binder. Building a legal claim means mapping decisions to harm: timelines, metadata, vendor invoices and complaint threads establish causation. Discovery — subpoenas, preservation notices and ESI requests — opens those sealed folders for review.
Emails, memos and board minutes often show ignored warnings, missed escalations and repeated excuses. Depositions and forensic pulls can link a supervisor’s silence to a pattern of nonresponse, reinforcing liability and opening damages avenues. A preservation letter paired with targeted custodial email requests often uncovers the internal threads needed for firm accountability.
Why Institutional Cases Broaden Recovery Options
A successful institutional claim can unlock remedies unavailable in individual suits. Beyond direct compensation for therapy and lost wages, courts can award damages for future care, relocation costs, and reputational harm. Punitive damages may further punish deliberate indifference or systemic cover-ups, signaling to boards and regulators that lapses carry financial consequences and civil penalties in some jurisdictions.
Settlements often include non-monetary change, including mandated training funds, independent monitors, and revised reporting procedures that reduce future risk. Combining compensatory, punitive, and injunctive relief widens options for survivors seeking repair and prevention. Keeping pay stubs and therapy invoices organized strengthens claims for lost income and care.
Survivor Impact and Broader Accountability
A courtroom settlement notice tacked to a hospital corridor can shift more than dollars. Public records, mandated reporting changes and required training reshape staff behavior, while formal apologies and reputational remedies give survivors a wider audience. When institutions face financial and regulatory scrutiny, boards rethink oversight and managers revise incident response to prevent repeat harm.
Cases often fund independent monitors, community reporting hotlines and survivor-led advisory panels that alter policy in concrete ways. Transparent benchmarks — regular compliance reports, accessible complaint portals and revisable consent forms — make institutional commitments measurable; a settlement clause for biennial independent audits provides an early metric and eases follow-up.
Accountability that extends beyond a single offender addresses the systems that allowed harm to occur. When overlooked warnings, poor oversight and weak policies come to light, they reveal how preventable risks became entrenched. Legal claims against organizations can secure compensation, but equally important, they press for reforms that strengthen reporting, hiring and safety practices. Survivors gain validation and resources while also seeing change ripple outward. Pressure on institutions to act turns individual cases into collective progress, creating safer schools, hospitals, workplaces and communities where protection is not an afterthought but a standard.